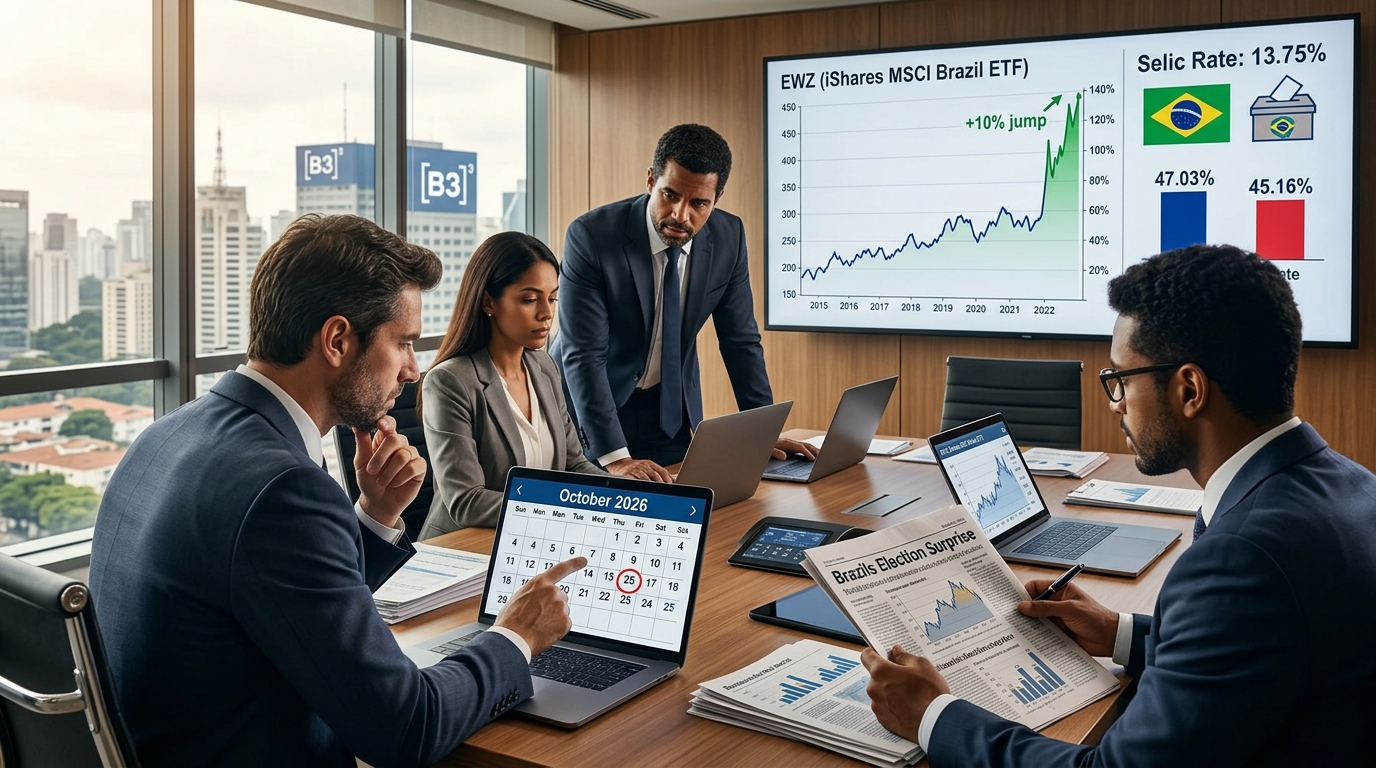
Brazil voted Sunday, October 4, 2026 and delivered the first genuine political surprise of the campaign. Flávio Bolsonaro, not Lula, led the first round, finishing with 47.03% of valid votes against the incumbent president’s 45.16%, according to the Superior Electoral Court with 99.99% of ballots counted. Pre-election polling, including a Datafolha survey published October 1 that had Lula five points ahead on valid-vote estimates, got the order of finish wrong. Markets noticed immediately.
The iShares MSCI Brazil ETF (EWZ) jumped about 10% in overnight trading. Petrobras (PBR) and Vale (VALE) ADRs each rose roughly 5% in the same session. The Ibovespa itself had already closed Friday at 192,115, up 2.63% on that day alone, as local investors had begun pricing in a favorable result. That pre-positioning matters: some of Sunday night’s gain is a continuation of a move already underway, not entirely new money.
What’s Driving the Market
Foreign investors read a Bolsonaro-led first round as a shift toward a more market-friendly policy environment. Flávio’s platform would replace Brazil’s production-sharing oil regime with concession-based licensing, abolish the 12% crude export tariff, and reorient Petrobras toward minority-shareholder returns rather than industrial policy. That is a materially different operating environment for PBR than four more years under Lula, whose government has leaned on Petrobras to pursue policy goals beyond dividend maximization.
But the 47-to-45 margin tells a more complicated story than the EWZ move suggests. The abstention rate hit 21.08%, the highest for a first round since 1998. Those 33.4 million non-voters outnumber the gap between the two finalists by more than 14 to 1. The runoff on October 25 is genuinely open, and runoff polling conducted before Sunday showed the two candidates statistically tied.
The Investment Opportunity
Three weeks of binary risk argues against taking the overnight EWZ pop at face value and building a full position at Monday’s open. The smarter question is how to hold Brazil exposure with defined downside through October 25.
For investors already long EWZ, the overnight gain creates room to layer in protective puts or reduce outright position size while keeping core exposure. For those looking to add, call spreads on EWZ structure the upside without committing full capital to a coin-flip runoff. PBR is the most election-sensitive single name: a Bolsonaro win could unlock dividend policy and pricing reform, but a Lula victory would likely reverse a significant portion of Sunday night’s gains in the ADR specifically.
Vale (VALE) behaves differently. Iron ore demand is driven by Chinese steel output, not Brazilian domestic politics, which makes it a relatively more stable way to hold B3 exposure through the vote. The banks, ITUB and BBD, sit somewhere between: they benefit from a Bolsonaro fiscal stance but are cushioned by the Selic regardless of who wins.
Risks to Monitor
The Selic, currently at 13.75%, is the other side of the trade that most coverage is ignoring. Brazil still carries one of the highest real interest rates among major economies, with headline inflation (IPCA) running about 4.22% over twelve months on the latest official reading. That rate level keeps the carry on BRL attractive for foreign holders of Brazilian fixed income, which can anchor the real even during equity volatility. But it also means domestic consumers and companies are operating under significant borrowing cost pressure, which caps how far a Bolsonaro equity rally can run on fundamentals rather than sentiment alone.
A Lula victory on October 25 would not necessarily collapse Brazilian assets, but it would likely trigger a reversal in PBR and pressure the real toward its recent highs. Dollar strength globally would compound that move.
Bottom Line
Sunday’s result was a genuine surprise, and the EWZ reaction reflects real repositioning, not noise. But a 1.87-point first-round lead with 33 million abstainers still to be persuaded is not a mandate, and three weeks is a long time to hold unhedged Brazil risk at a 10% premium to Friday’s close. The Selic provides some structural support through the carry. The binary on October 25 does not.