September 24, 2026
Bonus Content: Goldman Says China Bought 75% More Gold in July Than It Reported
If you still haven’t downloaded my “Simple Options Trading For Beginners” book…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge for this book, so do yourself a favor and download it now…
That way, no matter how much it is in the future, you’ll have a copy on your computer already.
Make sense?
FREE: Simple Options Trading For Beginners << Download Now
Good Trading,
Bill Poulos
P.S. Go here to save a copy of my “Simple Options Trading For Beginners” book to your computer before I start charging for it.
Goldman Says China Bought 75% More Gold in July Than It Reported
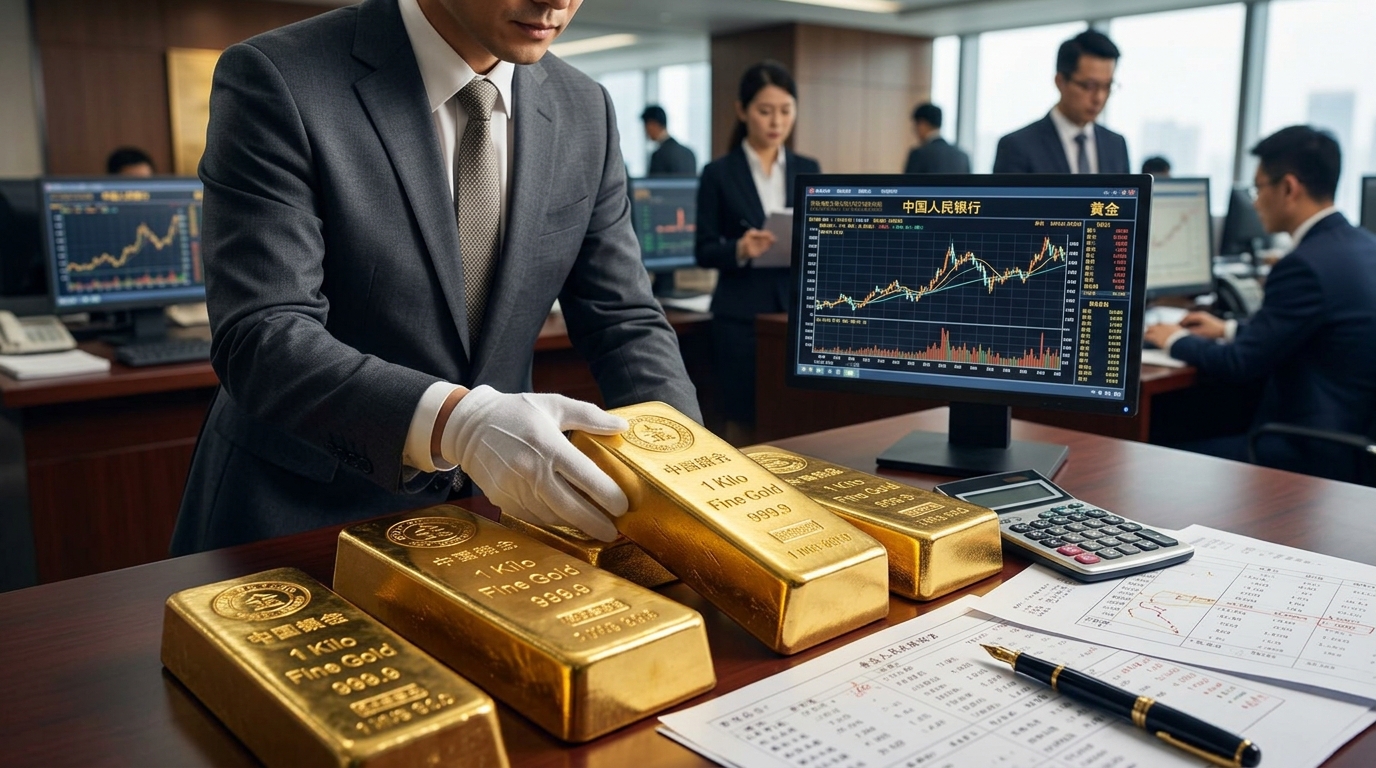
Goldman Sachs published a note this month affirming its year-end gold target of $4,900 per ounce, but buried inside it was a claim that matters far more than the price forecast itself. Goldman’s model puts the People’s Bank of China’s July purchases at 35 tonnes, roughly 75% more than the amount officially disclosed. If that estimate is right, the published data investors have been using to size sovereign demand is not just imprecise. It is structurally wrong.
The mechanics of how Goldman arrives at that figure are worth understanding. The gap comes from how Goldman tracks the market. Official reserve data can understate what central banks are buying, so the bank’s “nowcast” model also follows gold moving through London’s over-the-counter market and other channels into domestic vaults and third-party custodians. That methodology has teeth: China’s gold imports through August were reported by multiple outlets as above 1,000 tonnes, already surpassing the full-year total for 2025. The PBOC’s disclosed reserve additions over the same span are far smaller. The arithmetic doesn’t close without a much larger undisclosed accumulation somewhere in the system.
Official PBOC gold data is released through the State Administration of Foreign Exchange and is self-reported without independent third-party verification. Historical patterns have shown China periodically updating its official reserve figures through large single adjustments rather than continuous real-time reporting, suggesting accumulation may be ongoing well before it appears in published statistics. This is not a new observation. It is now being quantified in near real time by one of Wall Street’s most-followed commodity desks.
The implications for Goldman’s $4,900 call are double-edged. On the bullish side, actual sovereign demand running well above reported levels means the structural floor under gold is firmer than any publicly available dataset suggests. On a three-month seasonally adjusted basis, Goldman’s nowcast puts the global central bank buying trend at 91 tonnes per month, and the firm continues to see “net upside risk” to its $4,900 forecast. On the bearish side, a target built on data the model itself acknowledges is incomplete carries an unusually wide confidence interval.
Wednesday’s price action illustrated how exposed gold remains to a single macro data point. The trigger came from a survey: S&P Global’s September flash PMI showed U.S. private-sector output growing at the fastest pace in more than five years. Reports on the release also pointed to input-cost inflation accelerating to its quickest rate since October 2022, and the 10-year Treasury yield pushed above 5%, a level last seen in 2007. Spot gold ended September 23 around $4,289 per troy ounce, down roughly 1.5% on the day. That selloff tells you the market is still price-setting on real yields, even when sovereign buyers are accumulating quietly beneath it.
As of the World Gold Council’s latest published China update, gold accounts for about 7% of China’s total foreign exchange reserves, well below the far higher gold share held by the United States. That gap is the long-run fuel behind the whole thesis. China extended its buying streak to 21 consecutive months through July, and reserve managers execute multi-year programs, buying more ounces when prices fall.
The honest takeaway from Goldman’s note is not the price target. It is the methodology behind it. If the world’s most-watched central bank is running purchases roughly 75% above its public filings, every demand model in the market is working with an understated numerator. That does not guarantee $4,900. It does mean the sovereign bid is almost certainly larger, more durable, and more price-insensitive than any published figure shows.