Wednesday’s September CPI report was the same for every asset class: the U.S. Bureau of Labor Statistics reported that CPI rose 0.6% month on month in September and accelerated to 3.7% year on year, above the 3.6% forecast. What happened next depended entirely on what you owned.
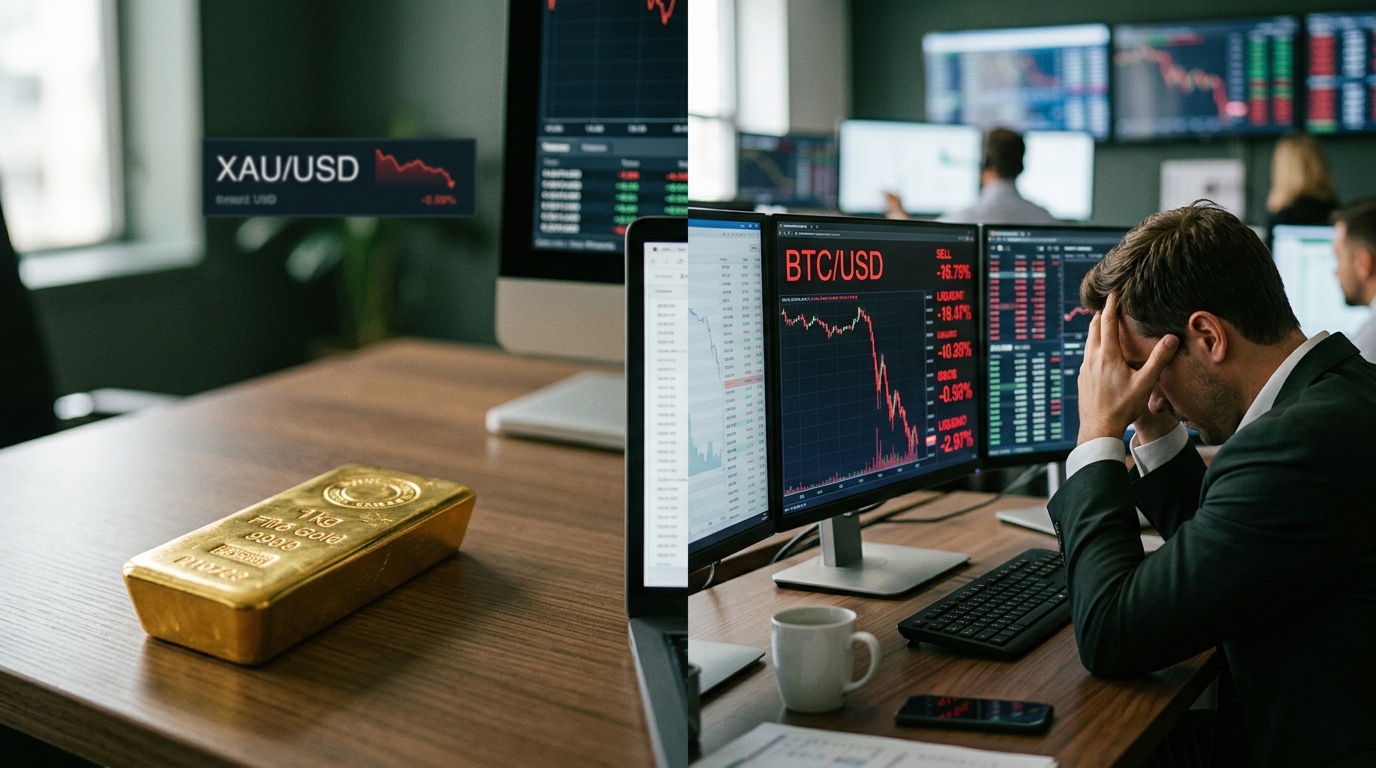
Gold traded around $4,145 on the morning of October 15, after selling drove it below $4,100 to test the mid-$4,060s. That is a decline of roughly 1%–2% from pre-report levels. Uncomfortable, but orderly. The hot data lifted the 10-year Treasury yield briefly above 5.32%.
Crypto did not steady. Bitcoin fell below $81,000 on October 15 as U.S. inflation concerns triggered another market selloff. CoinGlass showed roughly $942 million in liquidations over 24 hours in an early October 15 snapshot, with long positions accounting for about $863 million, or roughly 92% of the total. Nearly a billion dollars of bullish bets were erased in a single session, not because of any development inside the crypto market, but because a government inflation report came in one-tenth of a percentage point above consensus.
Ether’s damage was disproportionate. Ether traders took the biggest hit, with about $286 million in liquidations, while bitcoin traded near $81,000, down roughly 3%, and ether fell more than 6% to about $2,350. Ether made up nearly 60% of the forced closures across the two largest coins. That is a striking concentration for an asset with far less open interest than bitcoin.
The leverage structure behind ether’s losses is not unique to a single session. Bitcoin’s short-squeeze rally showed the same mechanical chain running in reverse, with forced closures driving price rather than organic demand.
The mechanism behind the carnage is worth understanding. Bitcoin dropped below $81,000, forcing more than $485 million in crypto positions to liquidate within a single hour, a flush of bullish bets that accelerated the selloff. The mechanism creates a feedback loop: forced selling adds momentum to downside moves, which triggers more liquidations at lower prices. Gold has no such feedback loop. There are no margin calls on a gold bar.
This is the argument that the store-of-value debate keeps circling back to. Bitcoin’s advocates point to its fixed supply and its independence from central bank policy. Both claims are legitimate. But a genuine store of value does not shed close to a billion dollars of positions in 24 hours because CPI came in at 3.7% instead of 3.6%. Gold fell on Wednesday too, for the same macro reasons. Core CPI rose 0.3% on the month and 2.6% year over year, while gasoline rose 9.1% and the energy index climbed 5.2%, showing that the oil shock is feeding directly into headline inflation. That is a real constraint on gold’s near-term upside, and no serious analyst is dismissing it.
The difference is scale and structure. Ethereum represented the largest identifiable share of the liquidation total, and about 92% of those positions were long. That level of one-sided leverage tells you something about the speculative character of the market, regardless of the underlying asset’s long-term merits.
Gold rebounded toward $4,150 on October 15 as yields and the dollar eased after the hot CPI reading. Crypto, by contrast, spent the Asian session absorbing forced selling from roughly 180,000 accounts, depending on the timing of the snapshot. One of those outcomes reflects how a mature store of value is supposed to behave under pressure. The other reflects what happens when an asset class is overwhelmingly held on borrowed money.
For precious metals investors, Wednesday’s session is not a reason to dismiss digital assets permanently. It is, however, a reason to keep asking which allocation actually holds its ground when the macro environment turns hostile, and which one turns hostile against itself.