September 23, 2026
Beijing Keeps China Vanke Alive.
Beijing’s strongest move yet to avert a Vanke default
Beijing moved decisively overnight to prevent China Vanke from tipping into formal default. Chinese financial regulators gave major banks informal guidance not to classify overdue Vanke loans as non-performing, to extend repayment deadlines, and in some cases to hold off collecting interest entirely. The directive landed as Xi Jinping arrived in Washington for a three-day state visit and summit with President Trump that both governments have framed as a stabilization exercise for the world’s most consequential bilateral relationship.
Your Free Options Book Is About to Vanish
In case you missed it… make sure you get your free “Simple Options Trading For Beginners” book before your link expires.
I eventually plan to charge money for this training, so do yourself a favor and download it now…
That way, no matter what it costs in the future, you’ll have a free copy.
Sound good?
Timing is rarely accidental in Beijing. The Vanke intervention and the Xi visit are two instruments of the same policy: projecting financial order at a diplomatically critical moment.
What’s Driving the Market
This is not the first time Vanke’s creditors have been asked to stand down. Back in January, lenders including Bank of China agreed to convert quarterly interest payments to annual ones and push all accrued dues to September 2026. That deferral window has now arrived, and rather than forcing a reckoning, regulators have extended it again through informal window guidance to some banks. How long the loans stay off bad-debt books remains deliberately open, Reuters reported, contingent on property market conditions and further discussions with Vanke.
The mechanism matters for industrial metals investors. Banks that classify a loan as non-performing typically step up collection efforts or demand additional collateral, compounding pressure on the borrower. By keeping Vanke’s loans in the performing column, banks avoid booking higher reserves, and Vanke avoids the cascade of stricter collection pressure that would otherwise force it to halt construction activity to conserve cash.
“Mind-Blowing Growth” – Wall Street Journal
It makes more money per employee than Google, Microsoft, Meta, or OpenAI.
It reportedly is experiencing “the fastest revenue growth of any company in in recorded history.”
Yet, while Nvidia, Google, and Amazon locked in shares… regular investors had no way in.
That changes today! Discover a secret backdoor in before the IPO [TICKER REVEALED]
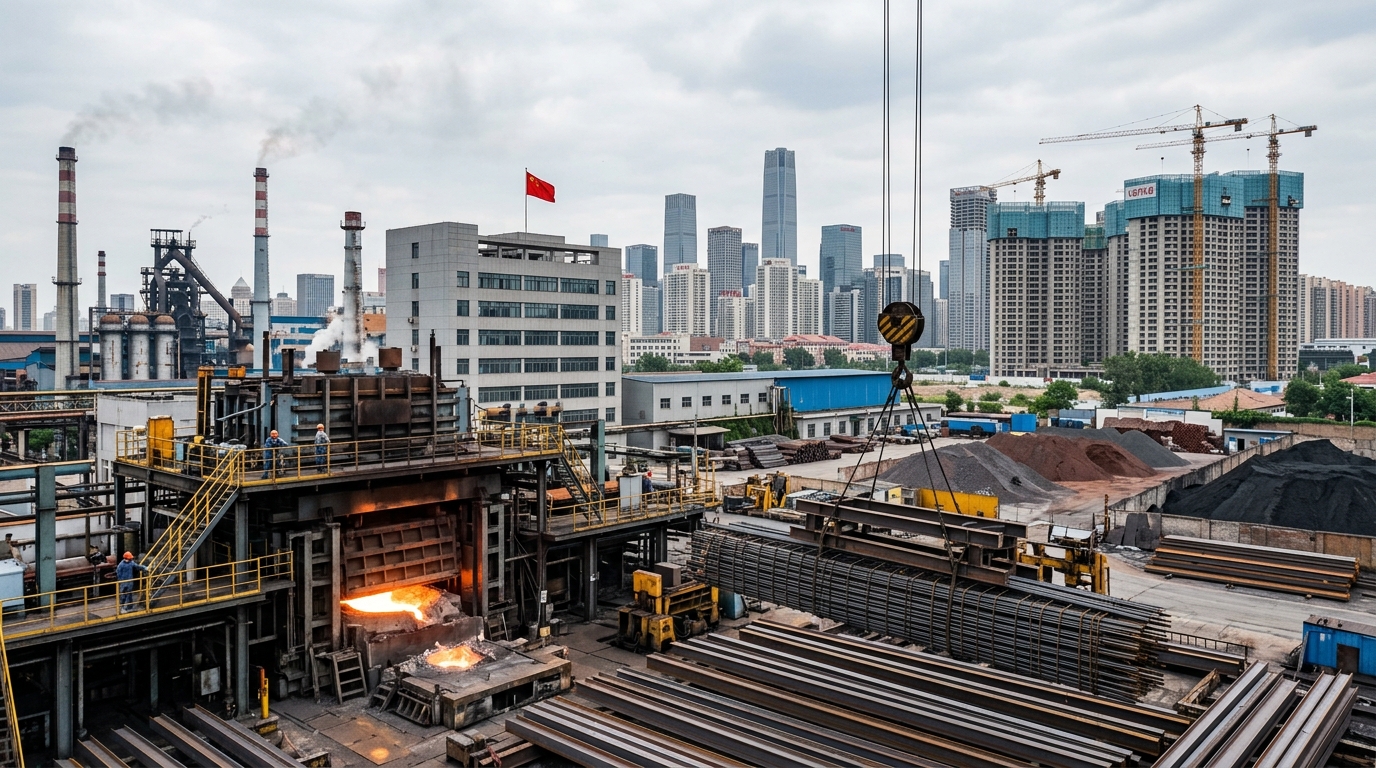
That construction activity is the link to metals demand. Vanke is one of China’s largest residential developers, with exposure across Shanghai, Guangzhou, and Shenzhen. In China’s current property environment, companies like Vanke have been pushed to prioritize cash collection, project completion, and inventory management, with a stronger focus on delivering ongoing developments rather than launching new ones. Keeping Vanke solvent keeps those completions moving. Completions consume rebar. Rebar consumes iron ore.
The Investment Opportunity
The consensus view on Chinese steel demand is bearish, and the data backing that view is real. First-half 2026 property investment dropped 18% from the same period in 2025, construction starts fell 23.4%, and property sales by floor area fell 11.6%. That is a genuine structural contraction, not a seasonal dip.
But the bearish read misses one distinction that matters for iron ore prices over the next six to twelve months: starts and completions are not the same variable. New starts are collapsing. Completions are also down, but policy support aimed at getting pre-sold homes finished can still cushion steel demand relative to what starts alone would imply. China’s recent stimulus policies have focused on clearing property inventories rather than boosting new starts, which limits the impact on steel demand but does not eliminate completion-related consumption.
For precious metals investors whose portfolios include broad commodity exposure or mining royalties with iron ore components, this distinction creates a more nuanced picture. Iron ore-leveraged royalty companies and diversified miners with Chinese offtake agreements may be pricing in a sharper steel demand decline than Beijing’s latest Vanke support implies. Financial authorities want to prevent a risk event at a developer so closely tied to a state shareholder, given the damage it could do to market confidence. That intent does not evaporate after one deferral round.
5 Nasdaq Stocks Under $5 That Aren’t What You Think
Most stocks under $5 come with a reputation. These don’t.
Each company on this list is tied to major trends like AI, cybersecurity, and next-gen infrastructure.
They may not have the spotlight yet, but they are building real businesses in real markets. That combination is not always easy to find at this price level.
Risks to Monitor
How long the loans would go unclassified as non-performing was left open, and Vanke reported a record loss of about 88.6 billion yuan in 2025 amid weak sales, which had eroded its cash position. Window guidance is not a restructuring. It is a pause. If the property market does not stabilize, the same conversation will recur in another six months, and regulators may find it harder to keep banks compliant each time. China’s property sector sank into a downturn in 2021, home prices are still falling, and a sustained recovery remains elusive.
The Xi-Trump summit introduces a separate variable. Xi’s visit comes with the one-year U.S.-China economic truce nearing its end, and any deterioration in bilateral relations would weigh on Chinese risk assets broadly, including developer stocks and the commodities tied to them.
Bottom Line
Beijing has made its preference clear: Vanke completes its projects. That is not an optimistic call on Chinese real estate. It is a practical observation about where state intervention is focused right now. The market is pricing iron ore and related industrial metals as if new starts are the only metric that counts. The completion pipeline, kept alive by interventions like today’s, tells a somewhat different story. Investors watching precious metals should not ignore the industrial metals signal embedded in this morning’s Vanke news: Chinese demand is being managed, not abandoned.