September 24, 2026
Bonus Content: Lululemon’s Supply Chain Bet Is Bigger Than the Brand Problem
Dear Reader,
According to the shocking new prediction from Marc Chaikin…
Elon Musk’s empire is doomed.
He just doesn’t know it yet.
Bottom line for U.S. investors?
Those who understand what’s coming could sidestep disaster…
While pocketing the biggest windfall in history, starting now.
AI investors who ignore what’s coming could “lose all,” he says.
That may sound hard to believe, but keep in mind…
Chaikin is a 60-year Wall Street legend.
His former client list has included multiple billionaires.
They have names like Paul Tudor Jones…
Steve Cohen, owner of the Mets…
Michael Steinhardt, of Steinhardt Partners…
And George Soros, founder of Quantum Fund…
His Chaikin Money Flow indicator is built into every Bloomberg terminal.
You could have followed his 20-factor Power Gauge system into Micron…
- Before the stock climbed 970% in one year…
- And into Celestica, before that AI stock soared 6,600%…
- And Nvidia, before it soared more than 50,001%…
As Mad Money host Jim Cramer says: “I learned a long time ago not to be on the other side of a Chaikin trade.”
Chaikin’s newest trade involves this radical new AI technology…
Launching before the end of 2026…
An innovation that will render all current AI data centers obsolete when it comes to major AI breakthroughs. (And yes, that includes Elon’s Colossus data center in Tennessee.)
Called “micro cluster” technology, these next-gen data centers take up 99% less space.
They take up 99% less electricity and water.
Yet they’re more than 1 trillion times more powerful than the #1 data center on earth today.
Marc’s research shows that when this replacement technology launches by the end of the year…
The U.S. government is quietly pouring billions into the company behind this breakthrough right now.
But the story has yet to break open in the mainstream media.
Meaning there’s still time to get in early.
Click this link now for Chaikin’s full research… including the name and ticker of the company behind this coming breakthrough.
Fair warning: This video contains timely information, including a detailed recommendation.
Chaikin reserves the right to take it offline at any moment.
Sincerely,
Vic Lederman
Publisher, Chaikin Analytics
P.S. We recommend checking out Marc’s presentation right now. Drop whatever you’re doing. When this company’s new AI tech launches, it’ll render all current AI tech virtually obsolete – instantly. How? By accelerating AI breakthrough times 360X. (Breakthroughs that were supposed to come in 5 years could come in 5 days.) The time to invest is now, he says. And he reveals the full story – and stock ticker – here, for free. Don’t delay. This launch will happen before the end of this year.
Lululemon’s Supply Chain Bet Is Bigger Than the Brand Problem
Heidi O’Neill officially took the reins at Lululemon on September 8, 2026. Her three decades at Nike make her the right kind of hire for a company trying to reconnect with consumers. But the more immediate problem she inherits is not a brand one. It is a logistics one, and the numbers are severe.
For fiscal 2026, Lululemon has said it expects a gross tariff impact of roughly $380 million, against forecast offsets of about $160 million within gross margin. That gap cannot be closed through marketing campaigns or ambassador deals with Lewis Hamilton. It has to come out of the supply chain itself.
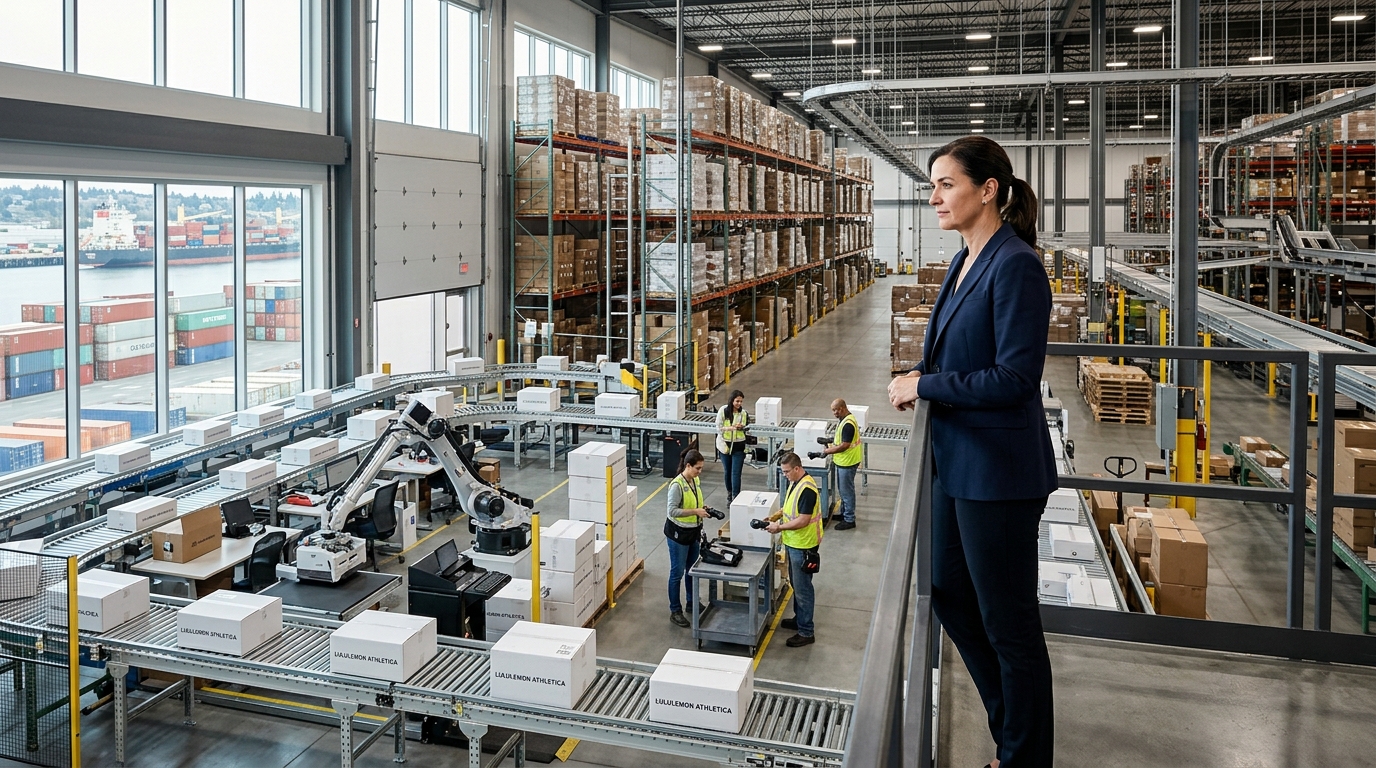
Management has been explicit about the three workstreams it is pulling. They are reducing inventory excess and shortening decision cycles, simplifying supply chain operations and non-merchandise procurement through network contract renegotiations and distribution center automation, and deploying AI across both the guest-facing side and the go-to-market calendar. On paper, that is a sensible sequence. The execution risk is real.
Go-to-market lead times are being cut from up to two years toward roughly one year, supported by AI-enabled planning and redesigned development processes. Compressing a two-year cycle in half while simultaneously managing tariff renegotiations and a CEO transition is an aggressive ask. Retailers that attempt simultaneous operational and commercial resets tend to execute neither cleanly.
The inventory picture gives one reason for measured optimism. Operating cash flow in the first half of 2026 reached $589 million, up 181% from $210 million in the same period a year earlier, driven primarily by strict working capital management and a sharp reduction in inventory purchases. That cash generation matters. Lululemon ended Q2 with $1.4 billion in cash and cash equivalents and has continued buying back shares, repurchasing 2.7 million at an average of $120 in Q2.
The demand side is harder to read favorably. Core leggings sales fell roughly 20% in Q2. Total revenue declined 4% and comparable sales dropped 9% in the same quarter. Because Lululemon is already priced near the top of the market, it has limited room to pass tariff costs on through higher prices.
The company’s return to full-price selling rests on three supply-chain levers: more product newness, fewer SKUs, and tighter inventory units. New-style penetration in North America is being lifted from 23% to around 35% in 2026. That bet on freshness only pays out if O’Neill’s team can get product to market faster than Lululemon has historically managed.
Risks to Monitor
Lululemon says it has no long-term contracts with its suppliers or manufacturers, and in 2025 worked with approximately 51 vendors for finished goods and 65 fabric suppliers. In a tariff environment where sourcing geography matters enormously, that lack of contractual anchor is a vulnerability, not a feature. Vendor renegotiations take time, and time is exactly what the new fiscal year guidance does not provide.
Full-year guidance calls for approximately 290 basis points of SG&A deleverage on top of an approximately 90-basis-point gross margin decline, producing an operating margin of roughly 16.1% against 19.9% in fiscal 2025. The supply chain rebuild is the floor under that number. If the offsets underperform, there is no obvious lever left to pull before O’Neill has even completed her first quarter.
Bottom Line
O’Neill’s Nike pedigree reads well in a press release. What matters now is whether she accelerates the logistics reset already underway or pauses it for a strategic review. Any delay in the SKU reduction and lead-time compression programs would push the full-price sales recovery further into 2027, compounding what management has already called a lost year for the top line. The supply chain is the investment thesis. Everything else is secondary.