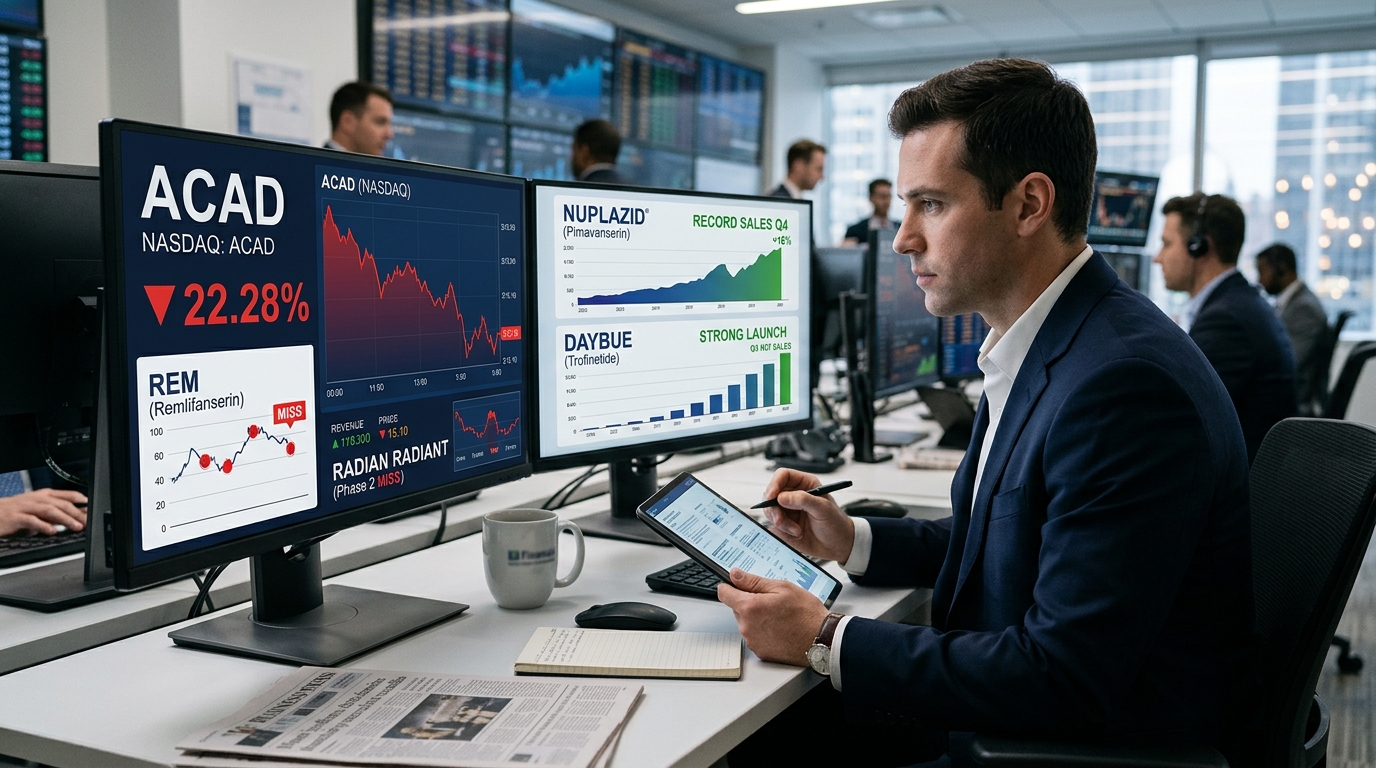
Monday was brutal for ACADIA Pharmaceuticals. ACAD sank 22.28% as investors revisited remlifanserin’s miss in the Phase 2 portion of the RADIANT Alzheimer’s disease psychosis (ADP) program. Volume on the session hit about 12.15 million shares against an average daily volume of roughly 2.28 million, and the stock touched a new 52-week low of about $15.10. That is the kind of session that closes accounts.
The science behind the sell-off is real but not quite as clean as the price move implies. The ongoing RADIANT program is evaluating remlifanserin, a serotonin 5-HT2A receptor inverse agonist, for hallucinations and delusions associated with ADP, and in the Phase 2 portion the drug narrowly missed statistical significance on the primary endpoint. The primary endpoint p-value came in at 0.0603 on the SAPS H+D scale. A miss is a miss. That framing matters because ACADIA’s own announcement called it a “narrow miss,” language that cuts little ice with investors who have seen that phrase before.
What gives the company its case for pressing on: the CGI-S-ADP secondary endpoint showed nominal statistical significance, with a p-value of 0.0077 for the 60-milligram dose. The company has also emphasized a favorable safety profile in Phase 2. The company plans to continue Phase 3 enrollments with an amendment removing the 30 mg dose, which showed minimal improvement across endpoints compared to placebo.
The regulatory and cost environment surrounding small biotechs has grown more complicated beyond any single trial result. Smaller biotech firms navigating the 100% pharmaceutical tariff are still waiting for clear guidance on exemptions, adding another layer of pressure on companies already absorbing pipeline setbacks.
None of that changes what happened to ACAD on Monday. What it does change is whether the sell-off priced in too much damage to a company whose existing commercial operation just had its best quarter yet.
ACADIA reported total revenues of about $342 million for Q3 2026, driven by record net sales of about $140 million for DAYBUE and about $202 million for NUPLAZID. EPS of $0.31 beat consensus expectations, and revenue of $342.29 million grew about 23% year over year. These are not the numbers of a business in distress. They are the numbers of a business whose pipeline bet did not pay off on schedule.
Context matters this week. ACADIA’s stumble arrived alongside a string of high-profile Phase 3 failures that rattled confidence in clinical-stage bets across therapeutic areas. At the American Heart Association meeting on November 7, results for Novartis’s pelacarsen showed the drug cut Lp(a) levels by 78% yet had no impact on major adverse cardiovascular events in more than 8,300 patients. Novo Nordisk’s ziltivekimab similarly reduced inflammation markers but did not reduce major adverse cardiovascular events in its ZEUS Phase 3 trial. Three prominent readouts in a week, three misses. The pattern does not invalidate any individual program, but it recalibrates how much credit the market is willing to extend for secondary-endpoint rationales and “narrow miss” framing.
More than 7 million Americans currently live with Alzheimer’s disease, and roughly 30% of those patients experience psychosis. Alzheimer’s disease psychosis remains a serious condition with no FDA-approved therapies with a primary indication for ADP. The unmet need is genuine. ACADIA’s Phase 3 program continues, and a Phase 2 readout in Lewy body dementia psychosis is expected in the fourth quarter of 2027.
At roughly $16.50, the stock trades at a trailing P/E around 10. Analysts’ consensus remains Moderate Buy, with an average price target of $31.55 and 13 Buy ratings against five Holds. That gap between current price and consensus target is wide enough to reflect genuine disagreement about whether remlifanserin’s Phase 3 ever closes it. The commercial business is not the problem. Figuring out how much to pay for a Phase 3 bet that just offered inconclusive Phase 2 evidence is exactly the problem investors are pricing right now.