Dear reader,
This stock trades for under $5 today.
Dr. Mark Skousen believes it could hit $50 by January 1st.
Why?
It’s one of the top stocks Elon Musk is targeting.
He’s revealing the key details in his latest briefing.
Click here for the story before it’s too late to take advantage.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
Stantec’s CA$9.2B Backlog Is the Real Story Before Thursday’s Numbers
When Stantec releases its third-quarter 2026 results after Thursday’s close, the headline figures will matter less than what the company’s backlog says about the next two years of infrastructure spending.
At the end of Q2, Stantec’s contract backlog reached a record of CA$9.2 billion, a 17.5% increase year over year, representing approximately 13 months of work. That is not a trailing indicator. It is a forward contract on a decade of civic necessity.
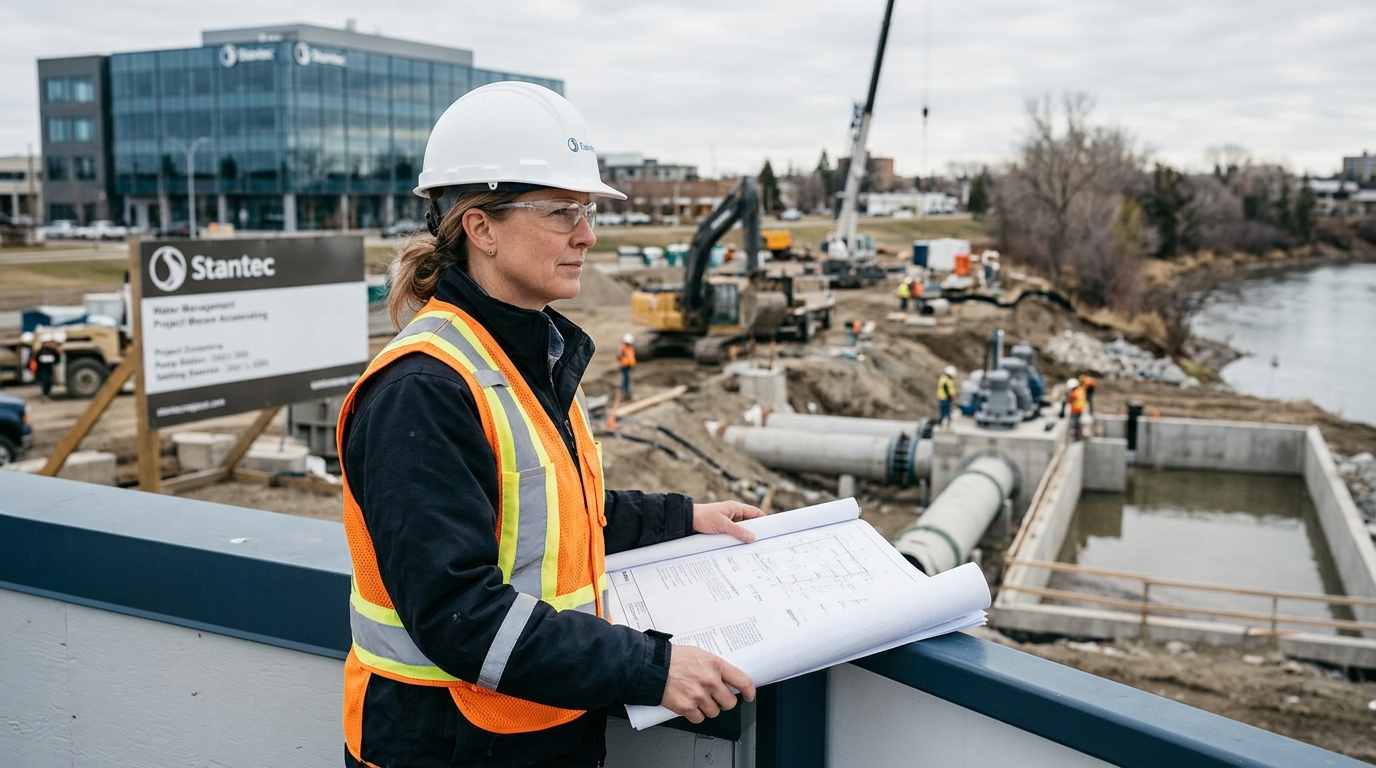
The water segment is doing the heavy lifting. The company’s water business delivered approximately 20% organic growth in Q2 through long-term framework agreements and public sector investments in water infrastructure across the UK, Australia, and New Zealand. North American momentum is equally real. Stantec’s water team was selected to provide preliminary design and evaluation services for the Drake Water Reclamation Facility in Fort Collins, Colorado, a 23 million gallon per day wastewater treatment plant. The project will modernize critical headworks infrastructure, improving debris removal and treatment reliability.
The macro context reinforces the case. A comprehensive report released in March 2026 by the American Water Works Association projects that the country will need between $2.1 trillion and $2.4 trillion in drinking water infrastructure investment over the next 25 years. That is a generational mandate, and Stantec is positioned upstream in every dollar of it. Unlike regulated utilities that deliver water directly to households, Stantec operates upstream in the value chain as the architect of the systems and environmental solutions that make modern water management possible.
Thursday’s call will also be new CEO Susan Reisbord’s first formal earnings presentation since taking the top role. Susan Reisbord became President and CEO of Stantec on October 1, 2026. She brings more than 30 years of experience in the industry, joining Stantec in 2021 with the acquisition of Cardno, where she was the CEO, before being promoted in 2025 to chief operating officer for North America, the company’s largest geographic operating unit. Investors will be listening for any shift in acquisition cadence or guidance language that signals her strategic priorities beyond the existing playbook.
The dynamic Stantec investors face is familiar across large-contract industrials. A headline contract award and a record backlog can obscure how much of that value is actually funded and ready to convert to revenue.
The financials heading into Q3 are solid. First quarter 2026 adjusted EBITDA increased 13.8% and adjusted EBITDA margin reached 16.9%, up 70 basis points compared to the first quarter of 2025. In Q2, adjusted net income reached $182.5 million and adjusted earnings per share of $1.61, an increase of 18.4%, driven by net revenue growth and strong operational performance.
The risk worth watching is federal funding continuity. The Infrastructure Investment and Jobs Act includes multiyear funding for fiscal years 2022 through 2026 for many programs, including EPA’s State Revolving Fund allocations tied to that window, and some authorities and funding provisions are set to sunset around September 30, 2026 without extensions. If Congress does not reauthorize at comparable levels, some U.S. project awards could slow in 2027. Stantec’s growing international footprint in the UK, Australia, and New Zealand provides a meaningful offset, but the domestic pipeline is not immune.
Valuation reflects the confidence the market already has in the backlog. The question Thursday answers is whether organic momentum in Q3 justifies that confidence or whether project ramp-up delays, flagged in the Q2 call, have started to clear. With roughly CA$9.2 billion in contract backlog and 13.0% organic net revenue growth in its Water business year to date through the first half of 2026, the foundation is intact. The burden of proof on Thursday is execution, not demand.