Two things happened last Friday that most markets are still digesting. Trump signed an executive order pausing new sanctions and tariffs on Russia authorized under the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026, just two days before key provisions were scheduled to take effect on October 18. Then, over the weekend, he posted that he does not want anything that would drive Russia away from the bargaining table. That comment is now the operative framework for U.S.-Russia policy.
The order uses the Graham Act’s waiver authority to suspend the application of duties and other measures, including tariffs of up to 500% on Russian imports and a 100% tariff increase aimed at the largest five importers of Russian-origin crude oil and natural gas that knowingly make new purchases on or after October 18, 2026. The explicit justification: a diesel deal Trump says serves the national interest. The politics are straightforward: the waiver comes as the administration argues the measures could worsen fuel-price pressure ahead of the November 3, 2026 U.S. midterm elections.
Stocks in Focus
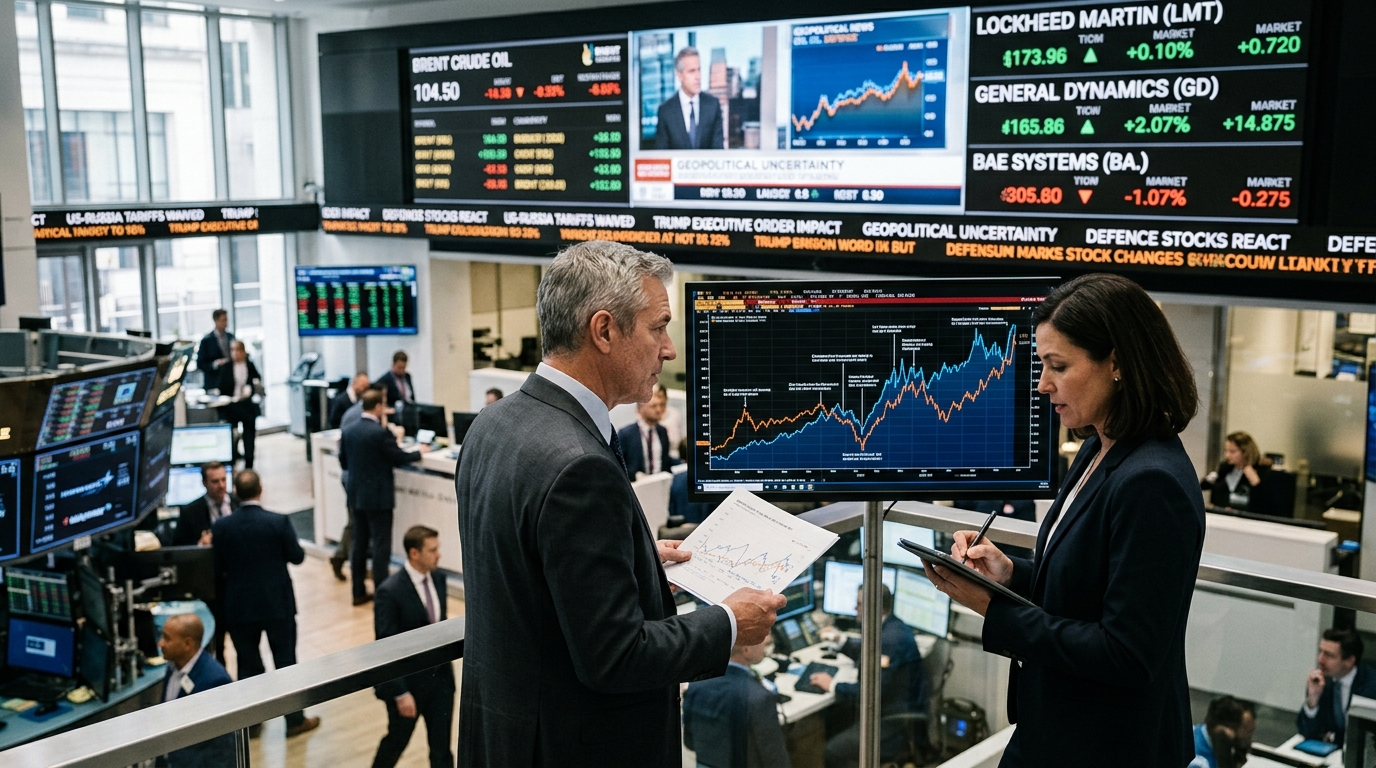
Brent Crude. Brent was trading around the $110 area on October 20, after settling at $109.55 on Monday. The waiver lowers the immediate risk of fresh, policy-driven supply disruption tied to secondary tariffs on major buyers of Russian energy, which can reduce some of the war-risk premium embedded in prices. A credible peace deal would push prices lower. A collapse of talks would send them higher again. The market is currently threading both risks at once.
Rheinmetall (RHM). Shares fell about 3.6% to 3.9% on Monday, closing around EUR 1,055.6. The trigger was a mix of diplomatic signals: Washington temporarily paused Graham Act penalties, while Putin indicated interest in a summit involving the U.S. and China. Rheinmetall shares are down about 30% year-to-date. Berenberg cut its rating from Buy to Hold roughly two weeks ago and trimmed its price target from EUR 1,600 to EUR 1,020, citing uncertainty over medium-term growth prospects.
Lockheed Martin (LMT) and BAE Systems. U.S. defence names face a softer version of the same pressure. Lockheed Martin, Northrop Grumman, and RTX have seen milder dips than European peers, since they are less tied to Ukraine-specific consumables such as ammunition, shells, and vehicles, and more to long-term U.S. programmes like the F-35, missile defence, and an Indo-Pacific focus. BAE has more European exposure and tracks Rheinmetall sentiment more closely on days like this.
The Diplomatic Picture
Putin has proposed a summit with Trump and Xi Jinping to discuss a possible settlement to the war in Ukraine. The Wall Street Journal reported the idea emerged during the October 9 phone call between Putin and Trump and would aim at an agreement favorable to Moscow’s interests. The Kremlin has said preliminary contacts have taken place, but there is still no agreed agenda or format. Trump has not accepted the trilateral meeting, while Beijing has signaled it would consider it if Washington approved.
The possible meeting could take place on the sidelines of the APEC summit in Shenzhen, where leaders are due to gather on November 18 and 19. Zelensky would not attend. Ukraine’s Foreign Minister has criticized the idea as unacceptable, warning it would encourage Putin to continue the war.
Secretary of State Rubio, speaking to reporters in Uzbekistan on Monday, said Ukraine and Russia should be focused on ending the war. Trump has defended delaying additional sanctions on Russia, saying he does not want to drive Moscow away from the negotiating table.
What Traders Should Watch
- Brent $108 support. The tariff waiver is bearish for the war-risk premium embedded in oil. A confirmed summit date would test this level quickly.
- Rheinmetall EUR 1,000. Given Rheinmetall’s very high valuation, any news related to peace in Europe could weigh heavily on sentiment. The stock is now below its 50-day and 100-day moving averages.
- Bipartisan pushback on the waiver. Some Republicans and Democrats have criticized the pause and the diesel deal. Congressional resistance could force a partial reinstatement.
- Summit confirmation at APEC. If Trump and Putin confirm a November 18-19 Shenzhen meeting, expect a sharp leg down in defence names and fresh pressure on Brent from reduced geopolitical risk premium.
The Cheat Sheet
Top Market Theme. Trump is pausing Russia tariffs and sanctions he signed into law to preserve a diesel deal, turning sanctions into a diplomatic variable rather than a fixed constraint.
Stock to Watch. Rheinmetall. Down about 30% year-to-date, its next move hinges on whether this summit produces a credible ceasefire framework or dissolves into familiar stalemate.
Sector to Watch. European defence. The sector responds faster and harder to Ukraine diplomacy than U.S. names. A summit headline is a same-day event risk.
Biggest Risk. Clarity arrives suddenly. A confirmed APEC trilateral date would hit Rheinmetall, BAE, and Brent simultaneously before most traders have repositioned.
One Thing to Remember. Even if the war ends, Europe is not returning to its old defence posture. The invasion fundamentally reset how European governments think about security, and defence budgets are structurally higher. The sell-off in defence stocks prices in diplomacy; it does not price in the decade of rearmament already locked into government budgets.