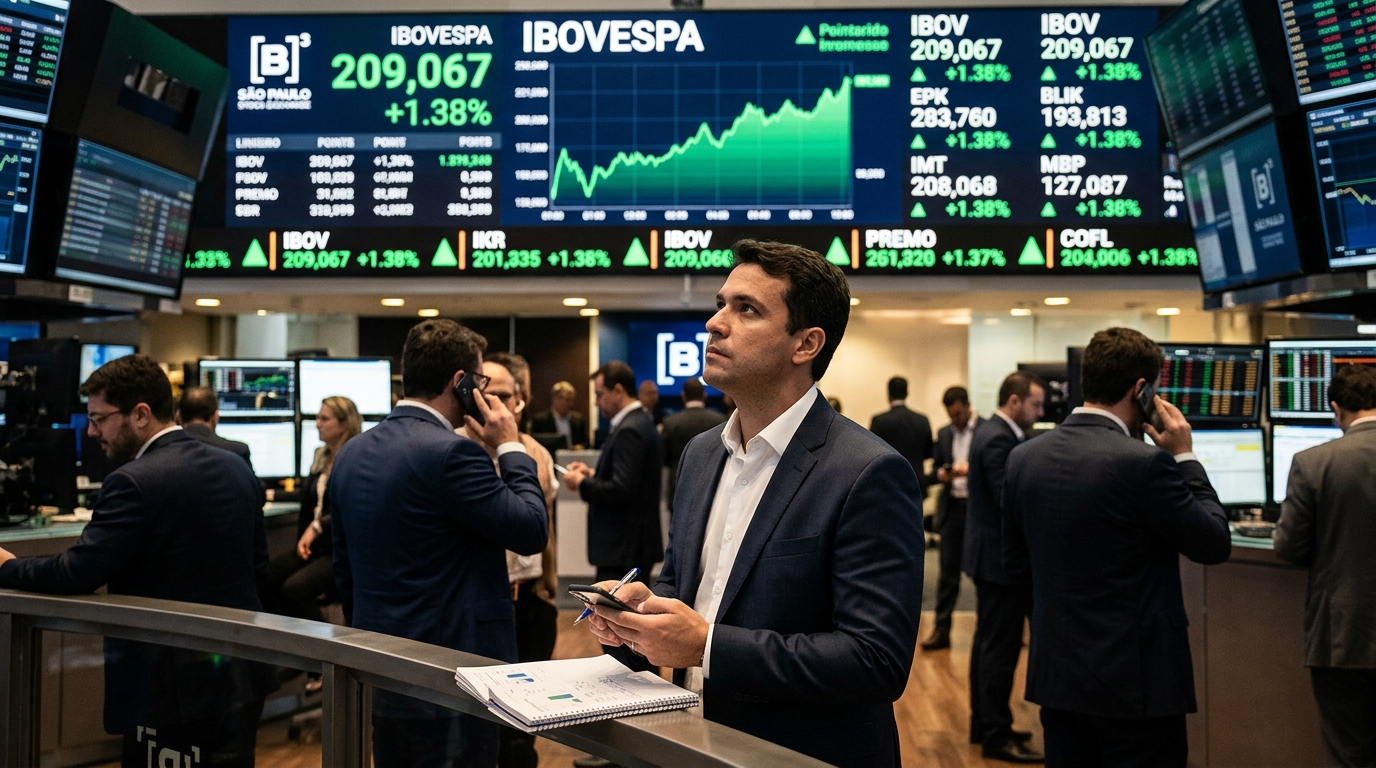
The Ibovespa does not wait for ballot counters. By the time Flávio Bolsonaro’s first-round lead was confirmed on October 4, traders had already moved. The index jumped 7.7% to a record 206,911.89 points on October 5, its biggest single-day gain since March 2020. It did not stop there. By Friday October 9 the index had climbed another 1.38% to a new record of 209,066.90, and the real was holding below R$4.99 per dollar.
The Datafolha poll published Thursday October 8 gave Bolsonaro 52% of valid votes to Lula’s 48% ahead of the October 25 runoff. The result still represents a technical tie given the poll’s margin of error of plus-minus 2 percentage points. Prediction markets are considerably less ambiguous: Polymarket showed Flávio Bolsonaro around the mid-80s as of October 9, but the Kalshi figure cited here could not be verified. Voters remain undecided; asset prices are not.
The reason prices moved so hard is not difficult to trace. Investors read Bolsonaro’s lead as raising the chance of a change of government and tighter spending. For a market that has spent years penalized by fiscal uncertainty and state interference in major companies, that is a meaningful shift. Petrobras surged about 8% in São Paulo on October 5, and its U.S.-listed shares rose roughly 11.5% on October 6 as investors reacted to the first-round outcome. EWZ, the iShares MSCI Brazil ETF, surged on October 5, but the precise 12.57% move to US$42.99 could not be verified from widely available end-of-day data. It ended the week at about US$43.55, up roughly 14% from US$38.19 on the last close before the first round.
The rally, however, is not uniform, and that divergence is worth reading carefully. The Petrobras ADR gained 16.9% over the week to US$25.30, while Vale’s U.S.-listed shares slipped over the same stretch. Vale’s relative weakness reflects its exposure to iron ore and Chinese demand rather than Brazilian politics. Inside the financial sector, the split is sharper. Banco do Brasil, the state-controlled lender, fell 6.42% on October 6, while Bradesco rose 4.40%. Banco do Brasil’s drop came after JPMorgan cut its rating on the shares to underweight. The logic is not hard to follow: a Bolsonaro-aligned government is expected to curb the lending mandates and dividend policy of state banks. Private lenders like Itaú Unibanco stand to benefit from a more level competitive field. Financials were about 35% of EWZ and energy about 16% as of early September, which means the ETF’s direction is heavily tied to exactly those two political risk lines.
The currency is doing its own confirming. The dollar fell about 4.2% against the real between October 2 and October 9, to roughly R$4.99. That is why EWZ, up about 14% in dollars, outran the Ibovespa, which gained about 8.8% in reais. A stronger real is itself a signal: it suggests global capital is comfortable returning to Brazilian assets, not simply that domestic traders are rotating.
The counterarguments are real. The Datafolha poll is the first post-first-round survey, taken over two days immediately after the vote when Bolsonaro sentiment was at its peak. Flávio still has not presented detailed fiscal plans. Whether Lula can win over the voters who backed neither finalist in the first round remains open. A shift in those undecideds, a stumble in the runoff debate, or a sharper-than-expected global risk selloff could close the gap faster than prediction markets suggest.
What to watch: any new Datafolha or Quaest poll before October 25 will carry significant weight. Watch the real; a move back above R$5.10 would signal that the market is reconsidering its confidence. Watch Banco do Brasil and Petrobras as the two names most directly wired to the policy debate. If Bolsonaro wins, the structural rerating in state-linked companies has further to run. If Lula closes the gap or wins, the retracement would be sharp and concentrated in the names that moved most.