October 31, 2026
Bonus Content: Gold Has Dropped $1,700 From Its Peak. The Plumbing Explains Why.
Editor’s Note: Our friend Louis Navellier has spent 47 years spotting big shifts before the crowd. He was early to Amazon, Apple, Microsoft, Google and Nvidia. Now he says the energy crisis everyone is worried about is quietly sending a wave of money toward one stretch of American coastline. Watch his free interview, or read more below.
Dear Reader,
In early February, 129 tankers a day were moving through the Strait of Hormuz.
Within a week… four.
The mainstream media covered it as a crisis. For a lot of countries, it was.
But here’s what the evening news mostly missed…
The countries that got burned aren’t sitting around waiting for the Strait to reopen. They’re lining up for American energy instead. Germany signed for 20 years.
Even Saudi Arabia, Qatar and Abu Dhabi – some of the richest oil nations on Earth – are putting billions into the American Gulf Coast – Texas and Louisiana.
The old energy powers are betting BIG on America.
See where all that money is going.
I’ve been doing this for 47 years. I’ve never seen a country’s position in the world change this fast.
And I don’t think energy is even the biggest part of the story.
What’s happening along that coastline is tied to something President Trump set in motion last year… something I’ve seen only once before in American history.
The last time, ordinary families who got in early collected income for years. Some of them passed that wealth down for generations.
I call this one America’s $31.5 TRILLION IPO. And I believe the Gulf of America could become the new Middle East.
Click here to find out what Trump is really building.
In my new interview with John Burke, I explain what’s going on… why the money is moving now… and the companies I’d want to own before Wall Street catches on.
It’s free to watch.
|
Regards,
Louis Navellier
Editor, Growth Investor
P.S. Most people are watching the price at the gas station. I’m watching who’s collecting the checks. Here’s the full story.
Gold Has Dropped $1,700 From Its Peak. The Plumbing Explains Why.
Gold closed Friday near $3,876, roughly $1,530 below the all-time high it set on January 29. The calendar drop looks dramatic. The cause is more instructive.
The most important development in precious metals right now is not a geopolitical shock or a central bank surprise. It is a slow, mechanical tightening in the pipes of U.S. short-term funding, arriving precisely when the Treasury is about to test long-bond demand at the worst moment of the cycle for duration buyers.
What the Plumbing Is Telling You
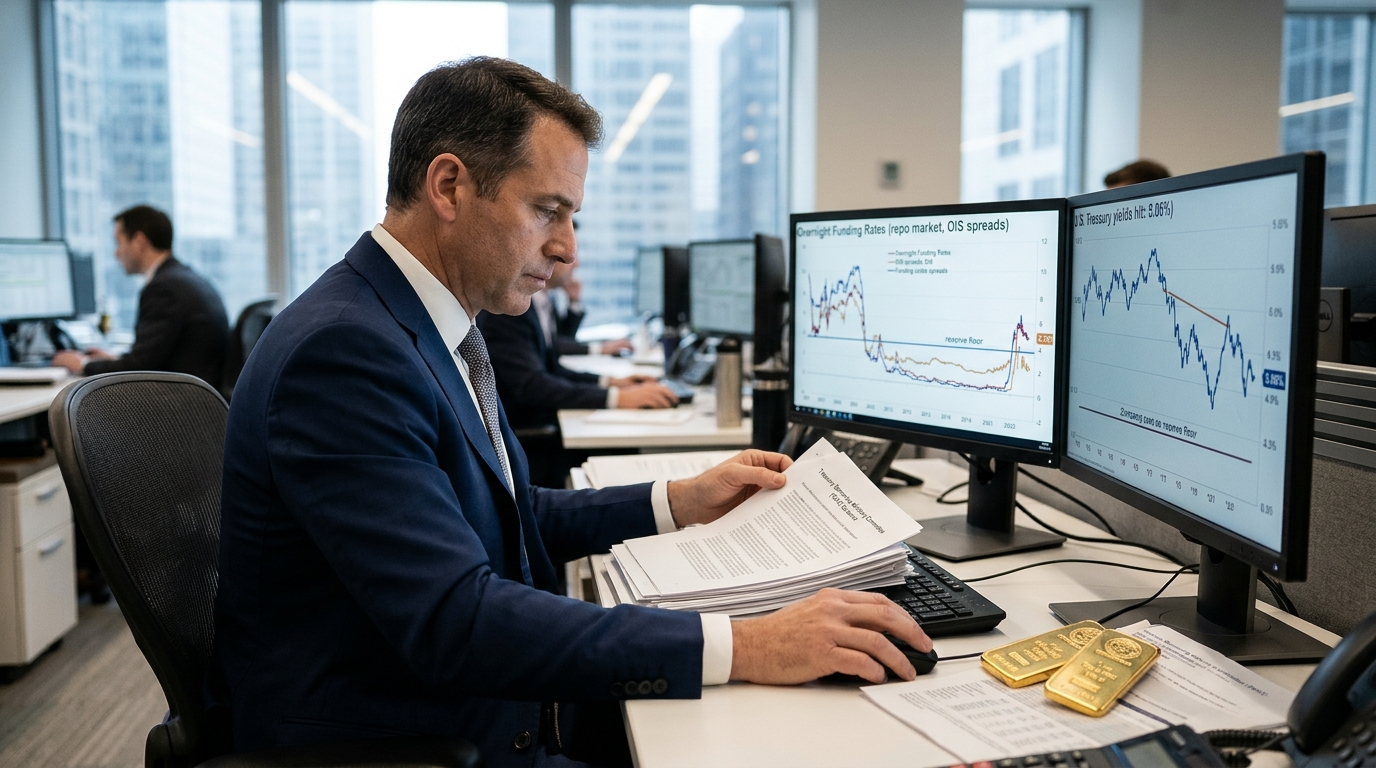
SOFR reached 3.95% on October 27, and held at 3.94% through October 29. That number matters because the Federal Reserve pays banks 3.90% on reserves parked at the Fed overnight. When SOFR trades above that rate, it means private repo markets are tighter than what the Fed itself offers, which is the opposite of the intended design.
The spread has widened from near zero to as much as 5 basis points above IORB across the late-October window. Bank reserves have fallen to roughly $2.89 trillion, a compression that reduces the buffer dealers rely on to absorb Treasury collateral. At the same time, the Treasury’s General Account sits above $1.0 trillion, money that is parked at the Fed rather than circulating through the banking system. The two forces together are draining private liquidity and making overnight funding incrementally more expensive.
Friday was a month-end turn, a date when dealers routinely window-dress their balance sheets for regulatory reporting. That amplified the stress. The 99th-percentile SOFR touched 4.04% on October 27, meaning the most stressed borrowers in the repo market paid about 14 basis points above the Fed’s reserve rate.
The 10-Year at 5% Compounds the Problem
None of this would be decisive for gold on its own. The second leg of the problem is duration.
The 10-year Treasury yield touched about 5.05% on October 28, the day the Federal Open Market Committee voted 10-2 to hold rates at 3.75%–4.00%. Two voters, Governor Lisa Cook and Cleveland Fed President Beth Hammack, wanted to hike immediately. Following that dissent, markets moved the probability of a December hike to roughly the mid-80% range. The 10-year has since pulled back to near 4.93%, but the fiscal arithmetic keeps it anchored near 5%: the federal budget deficit for fiscal year 2026 came in at about $2.0 trillion, and Treasury expects to borrow $628 billion in privately held net marketable debt in the October-December quarter.
The 10-year real yield, as measured by TIPS, stood at 2.67% on October 28. Gold peaked in late January when real yields were closer to the mid-1% range. Every basis point added since then raises the opportunity cost of holding an asset that pays nothing.
Wednesday Is the First Hard Test
Treasury is scheduled to publish its financing estimates on Monday, November 2, followed by the full quarterly refunding statement on Wednesday, November 4. That Wednesday release is the first supply signal since the 10-year closed at 5.31% on October 5, the highest close since 2002. The August refunding held nominal coupon auction sizes steady; the November statement will clarify whether that guidance holds and how much larger long-end buyback operations might become.
The refunding statement lands into a market already questioning whether there is enough natural demand for long-dated supply. Treasury’s decision to double long-end buyback operations revealed how thin the sovereign funding market had already become.
If Treasury signals it needs to issue more duration into a market already struggling to absorb current supply, real yields will face upward pressure again. Gold, currently about 28% below its late-January high, would face a renewed headwind before it has had a chance to stabilize.
What Would Reverse the Pressure
Three developments could materially shift the backdrop. First, a Treasury drawdown of the General Account, which would inject reserves back into the banking system and ease overnight funding stress. Second, a softer October CPI or payrolls report, reducing the probability that Cook and Hammack gain a December majority. Third, a refunding statement on Wednesday that actively increases long-end buybacks, absorbing some of the duration the market is being asked to hold.
A Treasury General Account drawdown would ease domestic reserve pressure, but foreign demand for that duration is its own variable. Japan’s roughly $1.1 trillion position in US Treasuries is itself at risk if rising JGB yields pull capital back home.
Until one of those catalysts arrives, the combination of SOFR above IORB, real yields near 2.67%, and a December hike probability in the mid-80% range represents the most hostile backdrop gold has faced this cycle. The price of gold is reflecting that. The question for investors is whether Wednesday changes the calculation.