The timing is almost theatrical. Hours after Newmont posted the most profitable quarter in the company’s history, spot gold slid below $4,000 for the first time since mid-July. Investors celebrating a record earnings beat woke up to a market that had already moved on.
The numbers from Wednesday night were genuinely impressive. Newmont’s Q3 adjusted earnings came in at $2.20 per diluted share, topping the $1.95 Wall Street consensus by 13%, on revenue of $6.36 billion. Free cash flow hit a third-quarter record of $1.9 billion, and the company generated $2.8 billion in cash from operations. Through the first nine months of 2026, Newmont has now produced $7.3 billion in free cash flow, roughly matching what it generated in all of 2025.
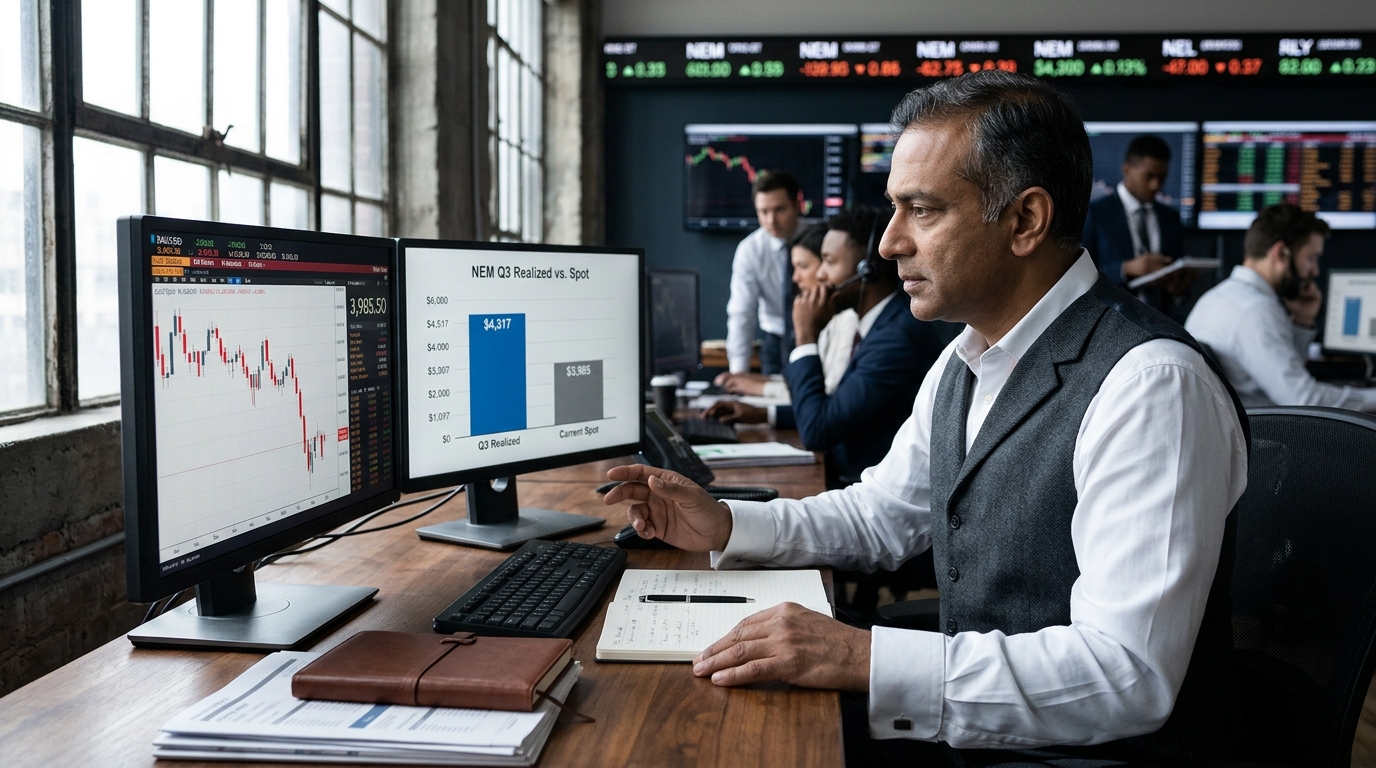
The engine behind those numbers: a realized gold price of $4,317 per ounce against all-in sustaining costs of $1,454 per ounce. That $2,863-per-ounce margin is the figure that matters most right now, because it is no longer the current reality.
What the Slide Actually Costs
Spot gold dropped as much as 0.9% to below $3,990 on Friday, extending the sharp selloff from Thursday. Brent crude pushed toward $114 per barrel after a fresh wave of attacks tied to the broader regional conflict deepened energy-supply fears, reigniting inflation concerns and lifting expectations that the Federal Reserve could tighten policy again later this year. Analysts at Global X ETFs characterized the gold selloff as “liquidity-driven,” the kind of forced selling that accompanies sharp cross-market de-leveraging rather than a fundamental reassessment of gold’s value.
But forced or not, the price is the price. At $4,000 spot against Newmont’s $1,454 AISC, the operating margin compresses to roughly $2,546 per ounce, about $317 narrower than last quarter. Applied proportionally to Q3’s 1.3 million ounces of production, that gap represents something in the neighborhood of $210 million in quarterly free cash flow that would not have been generated under today’s conditions. The $1.9 billion record becomes closer to $1.7 billion, which is still excellent but paints a different picture than the headline suggests.
Newmont also trimmed its full-year AISC guidance to approximately $1,520 per ounce, an improvement from its prior outlook. That tighter cost profile provides a wider cushion against further spot declines. Even at $3,900 gold, the margin would remain above $2,300 per ounce. The business is not threatened; the record-quarter optics are simply a Q3 artifact of a price level that no longer exists.
Cost discipline separates the survivors in a spot pullback. Barrick’s Q2 results showed how quickly a rising cost trajectory can overshadow a production beat and punish miner valuations.
What Survives the Correction
Two structural positives held regardless of where spot ends this week. First, Newmont ended Q3 with net cash of $3.2 billion, at the top of its target range, and $8.8 billion in total cash. The balance sheet absorbs volatility that would cripple less-capitalized producers. Second, the company returned approximately $1.9 billion to shareholders since the last earnings call, including $1.6 billion in buybacks, and has now retired more than 10% of shares outstanding since early 2024. That per-share math improves regardless of near-term spot moves.
The Red Chris block-cave feasibility study is nearing completion, with a full-funds decision expected early next year. Tanami expansion is targeting commercial production in the second half of 2027. Both projects were designed around far lower gold prices than even today’s depressed levels.
GDX is also worth watching. The ETF captures broad producer exposure and tends to lag spot moves in both directions. In a liquidity-driven selloff, miners often suffer disproportionately before fundamentals reassert. Newmont’s cost structure, at $1,454 per ounce last quarter and guided lower for the full year, is among the strongest in the peer group.
The Bottom Line
Newmont’s Q3 was real. The free cash flow was real. The margin was real. What is also real is that the gold price generating those results has since retreated by more than $300 an ounce. The question for investors is not whether last quarter was impressive, it was, but whether $4,000 is a floor or a way station. With the Fed meeting on October 27 to 28 and oil above $113, that answer is still forming. At current AISC, Newmont remains highly profitable at any spot level above roughly $1,500. That is the durable number. Everything above it is a function of where gold trades next week.