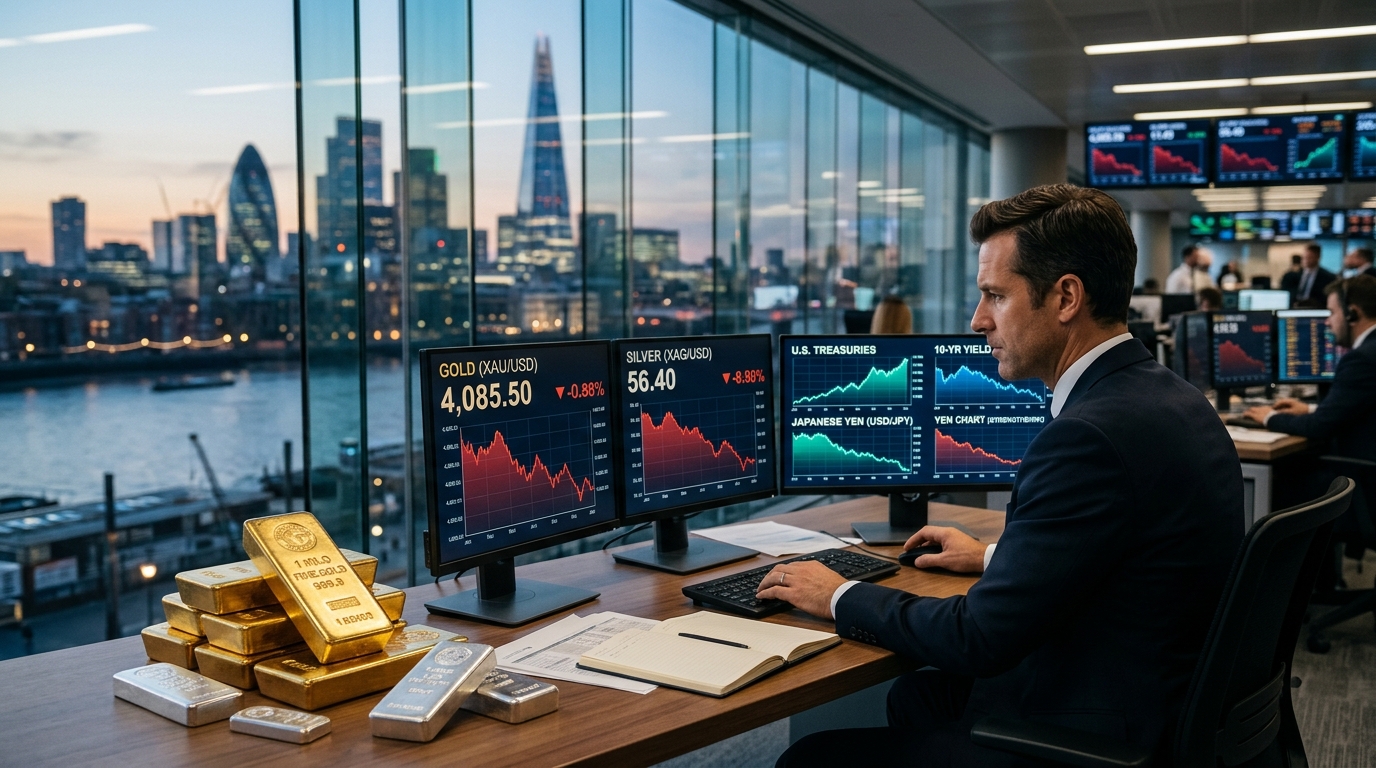
Gold was trading around $4,082 to $4,090 per ounce on Thursday morning, down from the previous session, as precious metals absorbed another wave of selling that had nothing to do with a lack of fear in the world. There is plenty of fear. It just is not going to metals right now.
Silver was trading in the high-$50s per ounce in late trading on October 21, and has pulled back sharply from early-October levels, even as it remains higher than a year ago. That one-month chart is the number that matters: silver has given back nearly all of its summer gains in roughly four weeks.
The reason gold and silver are falling on a morning when geopolitical fear is running hot is where the fear money actually went. The yen strengthened on haven demand while the dollar softened, as tensions around the Strait of Hormuz stayed in focus. Rising Middle East tensions also kept energy prices elevated and fueled safe-haven demand for U.S. Treasuries, with the 30-year bond yield falling three basis points to 5.38%.
Bonds and the yen absorbed the geopolitical bid. Metal did not. That divergence is not random.
When geopolitical stress also means oil is spiking, the inflation implications cut against gold in a specific way: even if a softer dollar helps on the margin, oil-driven inflation fears reinforce expectations that the Federal Reserve will stay restrictive longer. Real yields stay elevated. That is the environment gold finds hardest to navigate, even when the world is genuinely alarmed.
The broken correlation between geopolitical risk and gold matters for positioning, especially ahead of tonight. Newmont is set to release third-quarter 2026 results after the closing bell on October 22, with the conference call scheduled for 5:30 PM ET. The setup is uncomfortable. Newmont’s third-quarter performance is likely to have been impacted by weaker production and higher costs, with lower attributable gold production linked partly to the strategic divestment of non-core assets.
The company has guided to higher all-in sustaining costs in 2026, with gold by-product AISC per ounce at $1,680. Record realized gold prices have carried earnings through the year, but with spot gold now below $4,100, that cushion is narrowing at exactly the moment production and cost trends are moving the wrong direction.
The cost squeeze is not unique to Newmont. Barrick’s production beat was overwhelmed by a cost trajectory that sent shares sharply lower despite the headline ounces.
Published earnings estimates vary by source, compared to $1.71 adjusted diluted earnings per share in Q3 2025. The year-over-year improvement is real, but the stock has been pricing in a gold price that no longer exists this morning.
The investment case for Newmont has always rested on the leverage it offers to gold prices. That leverage works both ways. A beat on earnings per share tonight may do little for the stock if management’s cost commentary or production guidance disappoints, particularly with spot gold sliding back through a key psychological level during the reporting window. Watch AISC guidance and any revision to the full-year production range. Those two figures will matter more than the headline EPS number.
For broader precious metals positioning, the market is telling you something worth hearing: geopolitical escalation alone is not sufficient to drive sustained rallies in gold and silver when real yields remain elevated and oil inflation keeps central banks cautious. The haven bid needs to compete with bonds and the yen, and right now it is losing that competition.