Spot gold sits at $4,184 this morning, down 0.24% on the day and roughly 25% below the all-time high of approximately $5,590 set on January 28, 2026. Headline CPI is about to re-accelerate toward 3.6%-3.7% when September data prints Wednesday, October 14, at 8:30 ET. The dollar is at its strongest since early 2025. By every traditional measure, gold should be catching a bid. It is not. That is the story worth understanding before Wednesday at 8:30 ET.
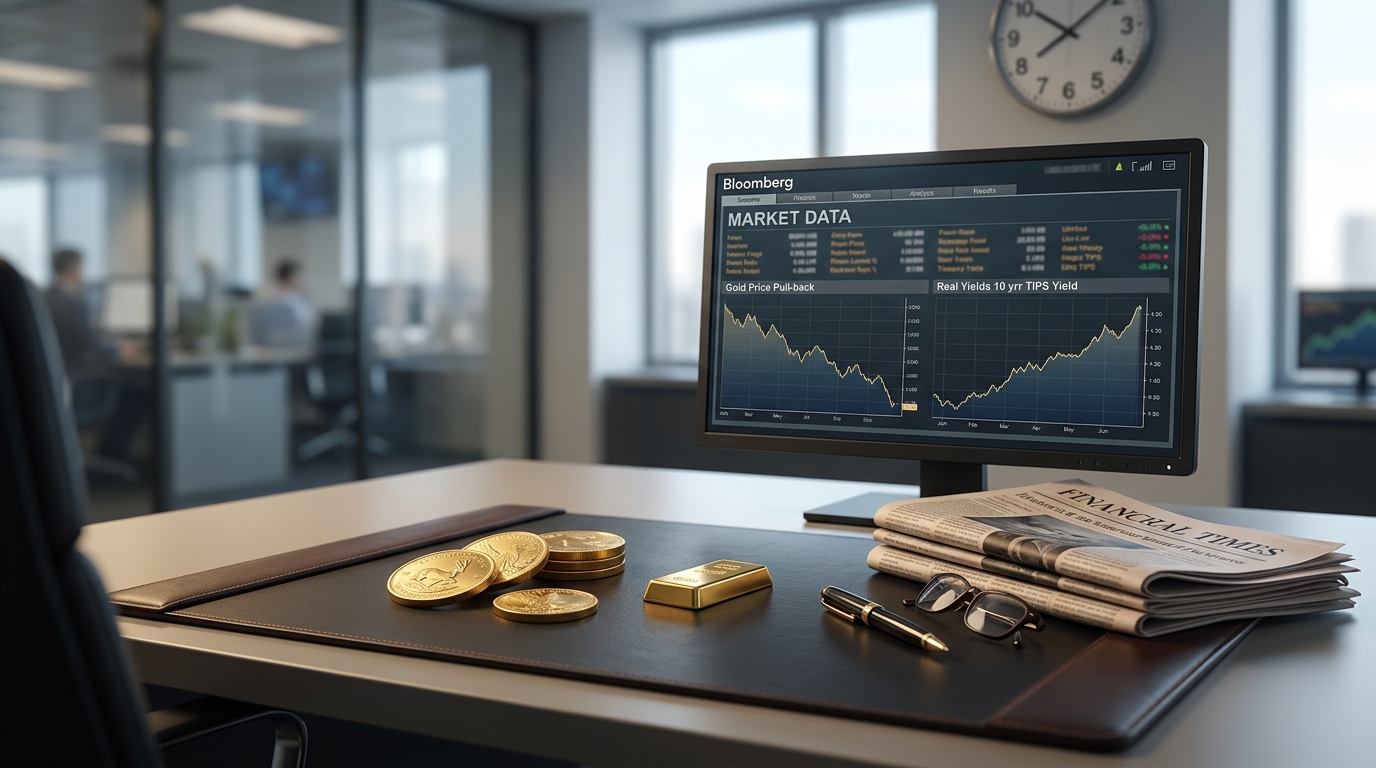
The explanation is not complicated, but it demands precision. Gold competes with the real yield on inflation-protected bonds, not with the inflation rate itself. The 10-year TIPS real yield, the Federal Reserve’s DFII10 series, last read 2.87% as of October 8. Since September 8, nominal 10-year yields rose and real yields rose, while breakeven inflation stayed roughly flat. This month’s move is a real-rate story, not an inflation story. Inflation is rising, but the bond market’s inflation compensation is not. That gap is doing the damage.
Gold fell to a multi-month low near $4,115 during a week when PCE inflation undershot forecasts and nonfarm payrolls collapsed to just 29,000, because a 24-year Treasury yield peak near 5.36% intraday overwhelmed both soft data points. The 10-year yield’s rapid progression from about 5.02% in mid-September to new highs in early October reflects a full reset in the long end, not a reaction to a single policy decision. The New York Fed’s September survey simultaneously showed one-year inflation expectations rising to 3.9%, the highest since May 2023. Higher inflation expectations, and gold at a two-month low, the paradox resolves through one variable: real yields.
What Wednesday’s CPI Actually Decides
The market expects headline CPI to rise 0.6% on the month, lifting the annual rate to around 3.7% from 3.4%, driven almost entirely by energy. The next Fed meeting ends Wednesday, October 28. Odds of an October hike have fallen to around one in four after weak September payrolls, with December still largely priced.
For gold, the relevant question is not whether headline CPI beats or misses, it is whether a hotter reading shifts the real-yield calculus. The bull case requires real yields to retreat below 2.40%; the bear case materializes if real yields hold above 2.85%. The 10-year TIPS last read 2.87% (October 8). Gold is squarely in bear-case territory. A CPI surprise that forces traders to price a December hike at higher conviction pushes real yields further in the wrong direction. That is how Wednesday becomes a test rather than a catalyst.
Historical parallels from the early 1980s, 2013-2014, and 2018-2019 consistently show that gold’s recovery precedes confirmed policy easing and is triggered by the market pricing a credible yield peak, not by any absolute yield level. The market has not yet decided whether 5.31%, the October 5 high close, was that peak.
The Investment Opportunity: Quality Over Optimism
Miners have amplified the drawdown. GDX fell 5.5% and GDXJ fell 6.2% in the week gold dropped 3.7% to $4,162, while the S&P 500 was essentially flat. That leverage runs both ways when real yields turn.
Among the majors, Agnico Eagle (AEM) presents the most defensible position in the current environment. Its all-in sustaining costs stood at $1,459 per ounce in Q2, leaving a $2,725 margin at today’s gold price, enough to sustain capital returns even with bullion well below the January record. Agnico reported record quarterly free cash flow of over $1.3 billion in Q2 2026, supporting record shareholder returns of $625 million in the quarter. Its long-term debt-to-capitalization is low, versus Barrick’s higher figure. A low-leverage balance sheet matters when bond markets are demanding about 5.24% on ten-year paper.
Newmont (NEM) carries scale: approximately 1.3 million attributable gold ounces in Q2, on track for full-year guidance of about 5.3 million ounces, and record Q2 free cash flow of $2.2 billion. The question is whether cost pressures narrow that margin if gold softens further toward the $3,850 bear-case level.
Risks to Monitor
The US federal budget deficit for fiscal year 2026 reached about $2.0 trillion, and Treasury bonds must be issued to fund it, expanding supply that requires higher yields to attract investors. That is a structural yield floor, independent of Fed policy decisions. A geopolitical catalyst, specifically a US-Iran deal, could compress yields toward 4.5%-4.75% independently of any Fed move, representing a potential upside catalyst for gold.
Bottom Line
The inflation hedge framing that dominated gold commentary for two years has broken down, and the data explains why. Real yields above 2.85% are the direct cost of holding an asset that pays no coupon. Until that number moves with conviction toward 2.40% or below, the path of least resistance for gold remains lower. Wednesday’s CPI is the first test: a soft core print that causes traders to walk back December hike odds would be the first genuine signal that the yield ceiling may be cracking. A hot energy-driven headline that hardens December expectations is not that signal. Know the difference before the open.