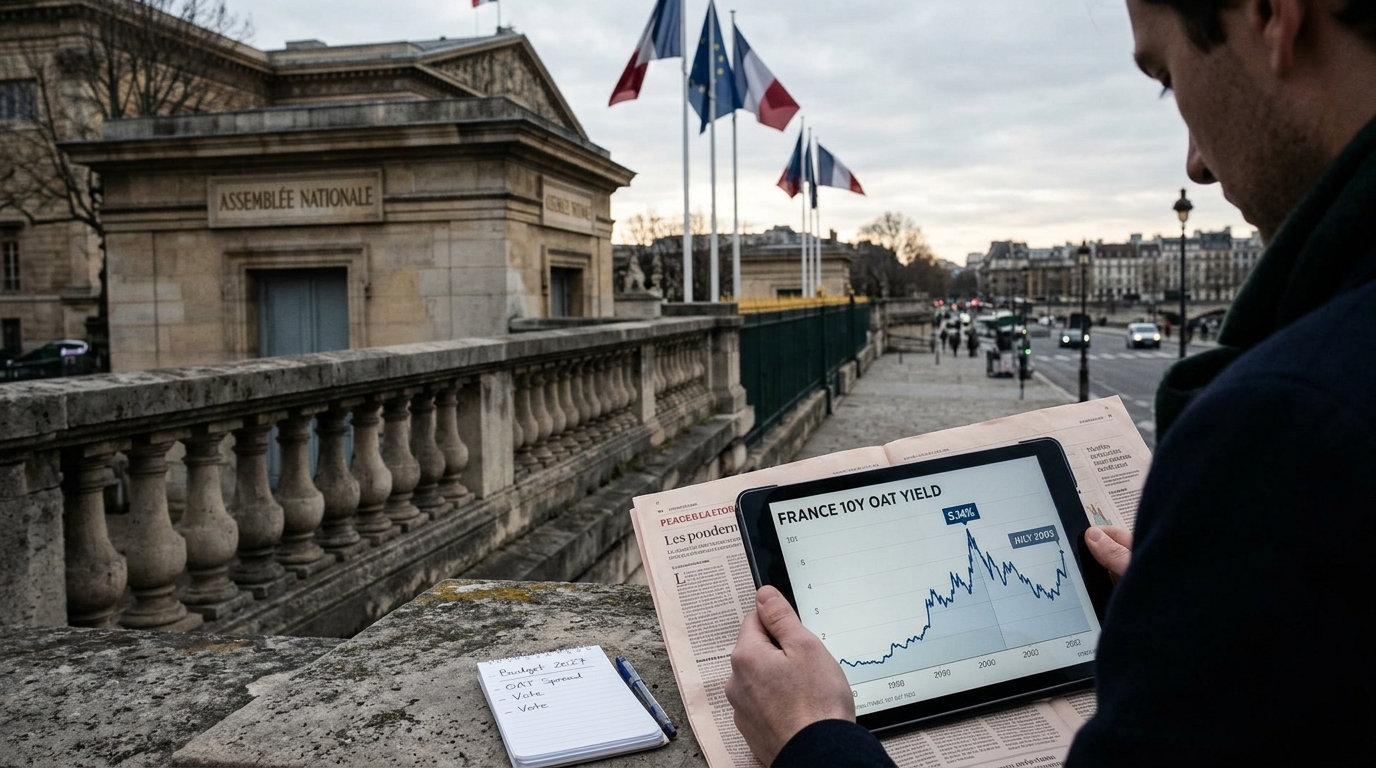
France’s ten-year OAT yield touched 5.14% on October 22, its highest since July 2002, before pulling back to 4.93% by Monday’s close. The spread over German Bunds peaked at 174.6 basis points that same day, the widest gap since the 2011 eurozone debt crisis, before settling at 156.4 bps on October 26. Today, the National Assembly resumes debate on the revenue half of the 2027 budget, with the vote on that section set for October 27 after the sheer volume of amendments forced a delay from the original October 20 date.
The market’s message, already delivered at those yield levels, is not subtle. It is pricing in a dysfunctional process, a watered-down fiscal package, and a government that will almost certainly need to bypass parliament to get any budget passed at all.
What the Bond Market Has Already Decided
The yield spike did not come from nowhere. Since the Hormuz crisis began earlier this year, ten-year OAT yields have risen 150 basis points, more than the US (+115 bps), Italy (+132 bps), or Germany (+83 bps). France is the hardest hit in the global bond sell-off, and the reason is largely domestic: fiscal deficits have remained above 5% of GDP for four consecutive years, and the political environment gives lenders no obvious path to improvement.
Moody’s reviewed France on October 23 and held it at Aa3 with a negative outlook, no downgrade, but no comfort either. That contained the immediate damage. The OAT/Bund spread eased roughly 18 bps on the back of it. But the relief looks thin against the underlying arithmetic. France plans to borrow a record €340 billion in 2027, roughly €1.3 billion for every working day, with public debt set to climb from 119.3% of GDP this year to 121.7% next year.
What the Vote Cannot Fix
Today’s resumed debate matters less than the calendar around it. Budget Minister David Amiel has already warned that amendments approved by the Assembly would worsen the deficit by roughly €10 billion. The finance committee rejected the revenue section 31 votes to 3 in early October. When the Social Security budget came to a vote on October 23, the Assembly overwhelmingly rejected its revenue half.
The precedent from the 2026 budget is instructive and sobering. Last year the Assembly rejected the revenue portion of the budget before the government forced it through via Article 49.3 in January 2026. Allianz Trade expects the same playbook this time around, with a final budget landing by year-end through ordinances or Article 49.3, keeping the 2027 deficit at roughly 5.3% of GDP, wider than the government’s 5.0% target.
Article 49.3 invites a no-confidence motion, and La France insoumise has said it will move to censure the government if it is used. Toppling the government requires 289 of 577 votes, which means the hard left and Le Pen’s RN must vote together, something they have so far avoided on budget questions.
Where It Shows Up
French bank stocks are the most direct channel. BNP Paribas, Société Générale, and Crédit Agricole all carry large domestic sovereign bond portfolios, and bank CDS spreads have been widening alongside OAT spreads. Foreign investors hold more than half of French government debt, and any further reduction in those holdings would compound the selling pressure on the bonds that underpin bank balance sheets.
The sovereign stress is not contained to the bond market. European equity strategists were already revising targets lower as French fiscal pressure and auto-sector shocks dragged the Stoxx 600 further from year-end consensus.
Long-term investors are already standing aside ahead of the April 2027 presidential election. The spread is unlikely to compress materially until either a credible fiscal path emerges or the political picture clarifies.
What Would Surprise
A clean parliamentary passage of the revenue bill, the outcome the bond market is not pricing, would be the genuine shock. So would a credible cross-party compromise that kept the deficit closer to 5.0% than 5.4%. Neither looks probable given the current alignment of forces. The more meaningful dates are October 27 for the revenue vote, November 17 for the full budget vote in the Assembly, and the S&P review on November 27. Allianz Trade’s baseline has spreads settling in a 120 to 150 bps range if a budget passes in some form. If the government falls, that range shifts to 150 to 175 bps, and the OAT briefly traded above the upper end of it last week.
The S&P review on November 27 lands in a global rate environment that is already doing damage. The 10-year Treasury at 5.13% is competing directly with sovereign debt that carries far more political risk, and that competition sets the floor for how wide OAT spreads can realistically compress.