Wall Street Has a Blunt New Name For What’s Happening To The Dollar
Gold hit a record $5,300 this January. The dollar hit a four-month low the same day. Wall Street doesn’t think that’s a coincidence.
They’re calling it the “Sell America” trade. And that’s not a fringe blog talking.
JPMorgan’s market intelligence team flagged it as potentially the market’s dominant narrative. Deutsche Bank pointed to investor concern about currency debasement and future inflation. BCA Research told clients the dollar debasement trades were running hot.
What are they all reacting to? Here’s what the financial press has documented:
✅ Fortune reported gold at a record $5,300 this January, up more than 22% year to date
✅ The dollar sank to a four-month low, falling 1.3% in a single day during the January slide
✅ Business Insider reported silver’s best-ever start to a year, tying the moves to mounting pressure on the Federal Reserve
And the White House? Asked about the falling dollar, the president called it “great.”
That’s why major institutions aren’t waiting to react. Analysts quoted by Fortune and Business Insider describe investors rotating out of dollar-denominated assets or hedging their exposure. Not panicking. Not predicting. Just quietly reducing how much of their wealth depends on one currency.
Gold has since pulled back from those January records. For the big institutions, that’s historically not a reason to look away. It’s when positioning happens.
For the everyday American who’s worked hard to build a nest egg, the tax code allows eligible IRA and 401(k) accounts to be diversified into physical gold and silver through a properly structured self-directed IRA, without taking a taxable distribution when completed correctly.
Download Your FREE Precious Metals Retirement Guide and learn the simple steps many savers are reviewing right now.
Historically, those who prepare ahead of financial turbulence have tended to fare better than those who don’t.
Who Passes the $6 Diesel Bill and Who Gets Stuck With It
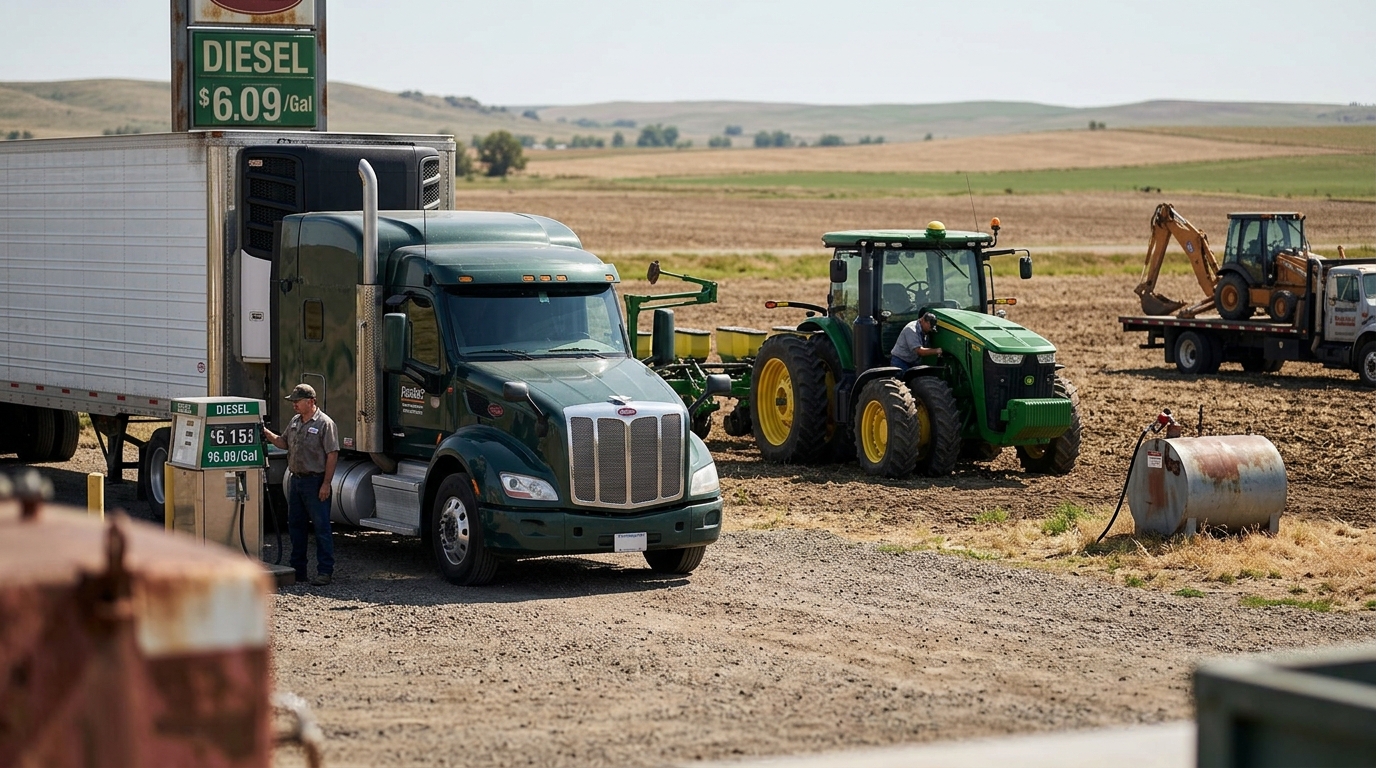
U.S. diesel prices rose above $6 a gallon for the first time ever last week, raising the risk of further energy-driven inflation just ahead of peak demand season. Then, on Monday, President Trump announced what he described as a diplomatic solution: he said Ukraine and Russia had agreed to stop hitting each other’s energy targets, though Ukrainian President Zelensky later described it as a proposal rather than a firm agreement. Markets seized on the headline. The real question for investors is more granular: with diesel at a record, who has the contractual machinery to push that cost downstream, and who absorbs it?
Why $6 Is Different This Time
The national average of $6.05 was up from $5.85 the week before and about $3.70 this time last year, according to AAA. That 63% annual rise is not seasonal noise. The shock is chokepoint-driven: the war with Iran has sharply reduced flows through the Strait of Hormuz, and the resulting squeeze has helped push diesel crack spreads to around $100 per barrel.
Critically, diesel and crude are not moving in lockstep. Relief at the crude level will not quickly translate to pump prices because the refining bottleneck runs on its own timeline. Even if the Ukraine-Russia pause holds, the global refining system does not heal overnight. A successful truce could stop the problem from getting worse. It cannot quickly repair the refining strain that has already been inflicted.
The Surcharge Winners
The clearest beneficiaries of sustained high diesel are the U.S. independent refiners sitting on the right side of the crack spread. The combined second-quarter 2026 profits of Marathon Petroleum, Phillips 66, and Valero Energy reached about $12.6 billion. Valero, Marathon Petroleum and Phillips 66 have more than doubled in 2026 as fuel crack spreads boosted refining margins. With crack spreads still elevated heading into Q3, those earnings estimates are almost certainly still too low.
Large logistics operators are also positioned to recapture cost rather than eat it. Large carriers like FedEx and UPS adjust fuel surcharges based on published fuel indexes. In April, Amazon rolled out a temporary 3.5% fuel and logistics surcharge tied to fulfillment fees for some third-party sellers. These companies built contractual pass-through mechanisms years ago. At $6 diesel, those clauses are real money.
Who Eats the Cost
The picture is far bleaker for operators without those mechanisms. Many small trucking operators cannot absorb much of the additional fuel cost themselves, and not all have access to fuel surcharges that can offset higher diesel prices.
The trucking industry was just coming off a record-long freight recession of more than 40 months from Q2 2022 through late 2025, and had been entering a new upcycle before facing this additional cost pressure. Small agricultural operations face comparable exposure. Diesel fuels the trucks, trains, and ships that bring goods to market, and it powers the machinery that farmers use to plant and harvest food. Harvest season is weeks away.
The Truce Risk Refiners Cannot Ignore
Trump’s claimed energy truce introduces a specific threat to the refiner thesis. Ukraine has stepped up strikes on Russian oil facilities and logistics infrastructure in recent months, seeking to raise the cost of the war for Moscow. The attacks have hampered Russia’s refining system, and Moscow banned diesel exports in July, removing supplies from an already tight global market. If strikes genuinely halt and Russia begins rebuilding throughput, some of the product-side tightness would ease over the coming months.
The track record here warrants skepticism. Past efforts to broker ceasefires covering energy targets have not yielded lasting results. No details were given on the timeline, the exact scope of the infrastructure covered, or the verification mechanisms for such a commitment. Meanwhile, the International Energy Agency’s September 2026 oil report states that in August, net exports of diesel and gasoil from the Gulf and Russia were 1.6 million barrels per day below their February level. A diplomatic announcement does not restore that volume.
Bottom Line
The $6 diesel record is not a single event to be reversed by a weekend post on Truth Social. It is the output of simultaneous supply damage across multiple theaters, and the companies best positioned to benefit are those that built surcharge mechanisms before the crisis arrived. Valero, Marathon Petroleum, and Phillips 66 sit at the center of a refining margin environment that the Ukraine pause, even if it holds, cannot unwind quickly. The losers are smaller operators in trucking and agriculture whose contracts predate a world where diesel costs 63% more than it did a year ago. That pass-through gap is where the real economic damage accumulates, and investors should watch it as carefully as the pump price itself.