September 14, 2026
War, Oil, and a Weak Dollar
The forces that should be fueling gold are instead feeding the headwind against it.
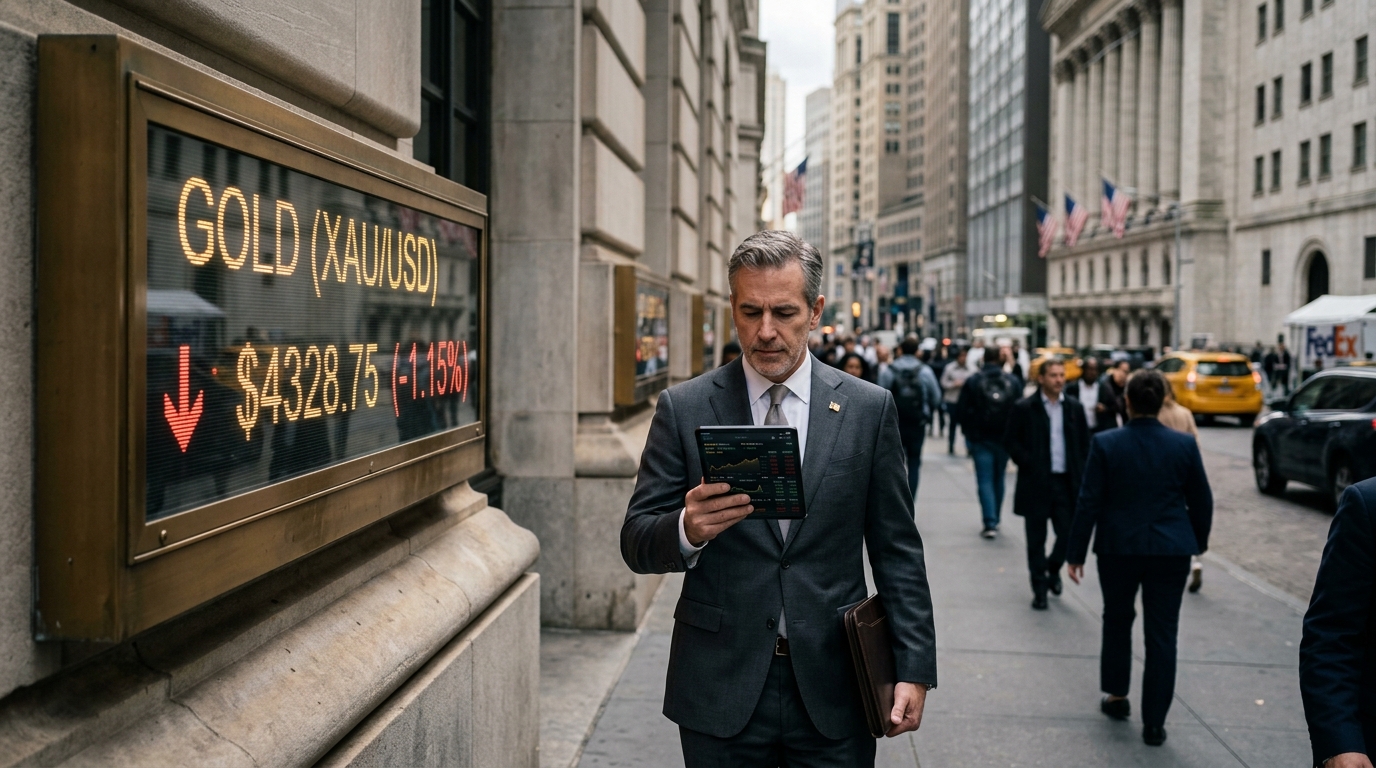
Gold near $4,330 this morning is supposed to be a contradiction. The U.S. is conducting strikes against Iran. Oil briefly reclaimed $100 a barrel. The dollar has weakened. Central banks bought more gold in a single quarter than at any point in the modern data series. And yet bullion has fallen for three consecutive weeks, sitting roughly 21% below the $5,589 record it set in January. Silver, trading near $64, is almost 47% below its own all-time high of $121.67, reached January 29.
In at 9:35 AM. Out by 10.
I call it the “Opening Bell Breakout.” It’s the same setup I used to catch moves like 113% on GOOGL and 240% on META. I trade one simple 15-minute window each morning – and I’m usually done by 10 AM.
The market is not broken. It is sending a clear message about what dominates right now, and that message is real yields.
What’s Driving the Market
August’s core CPI rose 0.3% month-on-month, against a market consensus of 0.2%. Coming on the heels of a hot PPI reading, headline producer inflation accelerated to 5.4% year-on-year from 4.8% in July. The combination pushed Fed rate-hike odds sharply higher. Markets are now pricing an 87% probability of a 25-basis-point increase at the September 15-16 meeting.
Here is the problem for gold bulls: this inflation is not the kind that lifts metals. The same Middle East conflict that creates geopolitical risk for gold is simultaneously driving higher inflation, higher oil prices, and elevated yields, counteracting safe-haven demand. War and an oil shock are feeding the rate-hike cycle rather than overriding it. The 10-year real yield stood at 2.55% as of September 10, a level that makes a non-yielding asset like gold expensive to hold relative to inflation-protected Treasuries. Higher interest rates typically weigh on gold because the metal does not pay interest, making yield-bearing assets relatively more attractive.
Sub–$1 Copper-Gold Explorer Has Major-Company-Funded Drilling
Copper is at record highs. Gold just blasted to $5K. Yet one little-known Australia-focused copper-gold explorer still trades below $1 as it advances multiple projects across two premier mineral belts. Most importantly, drills are turning – with one of the world’s largest gold producers funding the work. Add a deep treasury, tight share structure, pending drill results, and potential new deals, and this under-the-radar small-cap has all the right ingredients for a major breakout.
Silver faces a compounding problem. The gold/silver ratio has widened as silver bears the brunt of rate-hike anxiety, its industrial profile leaving it more exposed than gold to tighter monetary policy.
The Investment Opportunity
The central bank bid is real, and it deserves more attention than it is getting. Central banks globally bought a record 289 tonnes of gold in Q2 2026, five times the revised Q1 figure and 62% higher year-on-year, with Poland and China leading reported purchases as reserve managers focus on diversification and protection against geopolitical and financial risks. That buying came even as the LBMA gold price averaged roughly $4,506 per ounce during the quarter, 37% above its year-ago level. Sovereign buyers are not momentum traders. They accumulate on weakness, and they will still be accumulating after the Fed meeting ends Wednesday.
The World Gold Council’s 2026 Central Bank Gold Reserves Survey shows 89% of reserve managers expect global gold holdings to rise over the next 12 months and 74% anticipate lower U.S. dollar holdings over the next five years. That structural rotation does not reverse because of a single rate decision.
For investors positioned in GLD or the miners via GDX, the question is less whether the central bank bid reasserts and more when. Producers including Newmont (NEM) and Agnico Eagle (AEM) are generating meaningful free cash flow at current prices; both entered this year pricing in far lower gold. The pain in the miners is a sentiment story more than a fundamental one at these gold levels.
Inside the Nuclear Revival Reshaping Energy Markets
Governments worldwide are investing billions to revive a proven energy source. Supply chains are tightening, demand is rising, and select companies stand to benefit. The Nuclear’s Second Act report explains what’s happening next.
Risks to Monitor
The case for metals does not collapse here, but it needs a catalyst to shift. Fed Chair Kevin Warsh’s press conference following the September 16 decision matters as much as the hike itself. If Warsh signals the tightening cycle is near its end, real yields could peak and the central bank accumulation story takes center stage again. If he leaves the door open to further hikes, gold faces additional pressure toward the $4,286 technical support level that analysts are now watching closely.
The risk to the bullish thesis is a sustained period of 2.5%-plus real yields with no clear Fed pivot signal. That is what killed gold’s momentum from January through today. The risk to the bearish thesis is that sovereign buyers absorb every dip and the market eventually resets for the structural dollar diversification underway.
Bottom Line
Gold near $4,330 is not failing as a hedge because the world is calm. It is failing because the same conflict driving investors toward safety is also driving the inflation reading that forces the Fed’s hand. Real yields at 2.55% are the most powerful force in this market right now, stronger than war risk, stronger than dollar weakness, and strong enough to offset record central bank demand. What changes the picture: a credible signal from the Fed that rates have peaked, at which point 289 tonnes of quarterly sovereign buying and a structurally weaker dollar become the dominant variables. Until Wednesday afternoon, patience is the position.