Most investors still think of Clover Health as a money-losing insurer that leaned too hard on its own hype. The numbers from the last twelve months tell a different story, and one development from last month makes the old framing genuinely obsolete.
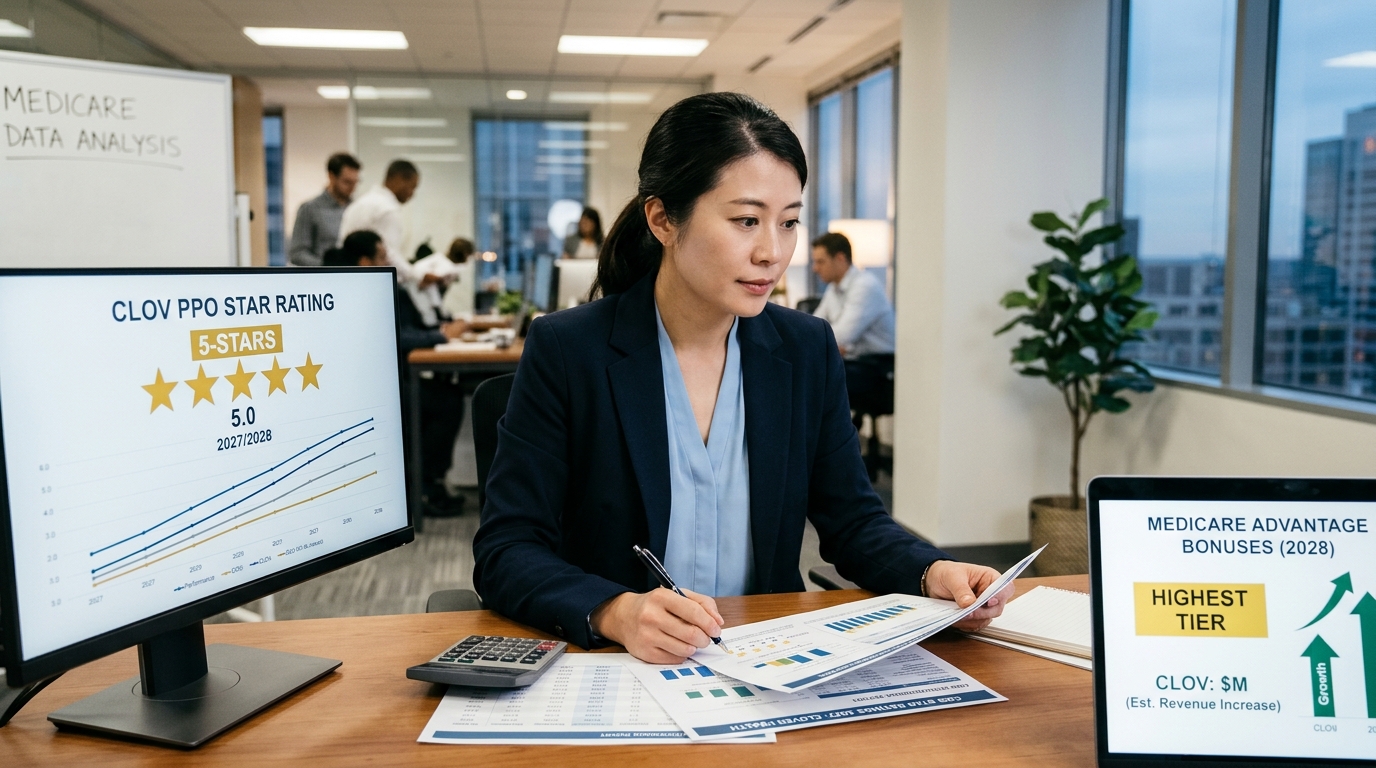
CMS awarded Clover’s PPO Medicare Advantage plans a 5-Star rating for 2027, with its HMO plans receiving 4.5 Stars. Those ratings will impact payment year 2028 and allow year-round enrollment for Clover’s PPO plans. That continuous enrollment window is the part worth sitting with. Competing plans can only recruit during the annual election period. Clover can recruit every single month of the year.
CVS Health’s Aetna and other large Medicare Advantage carriers are currently in litigation against CMS challenging 2027 star ratings they say were depressed by the agency’s use of measures that were not properly adopted, and that threaten their own bonus payments. Clover is on the opposite end of that dynamic, having benefited from the ratings process rather than contesting a demotion in court. When the biggest names in managed care are playing defense, a small plan holding a 5-Star designation is a structural beneficiary of their distraction.
What the AI Platform Actually Produces
The Clover Assistant is the mechanism behind the rating. The platform draws on more than 100 data sources and AI models to identify and treat chronic conditions earlier, and the company says it is linked to lower hospitalizations and earlier diagnoses for kidney disease and diabetes. Those are not marketing claims. The company says clinicians using the technology have been associated with chronic kidney disease stage 3 diagnoses occurring 18 months earlier and diabetes treatment beginning 36 months earlier compared with cases where physicians did not use the platform.
The financial translation is becoming visible in cohort data. Insurance gross profit per member per month is approximately $70 higher in year two than in year one, and roughly $85 higher in year three than in year two. As the membership base ages inside the model, the economics compound without requiring proportional cost increases.
Where the Numbers Stand
At the UBS Global Healthcare Conference on November 9, 2026, Clover outlined a business that is still growing quickly but is also starting to show more earnings power, with management noting better-than-expected medical trends and a strong competitive position heading into 2027. Year to date through Q3, the company reported $97 million of adjusted EBITDA and $62 million of net income, while membership grew about 50% year over year.
Medical trends were better than expected in inpatient care and Part D, though outpatient utilization ran higher. That outpatient pressure is real and worth watching. It is one reason management stopped short of issuing formal 2027 guidance on the Q3 call.
Risks to Monitor
The 5-Star status for the PPO plans was calculated by CMS excluding 20 disputed measures pursuant to a May 2026 court decision that is on appeal. If that appeal reverses the lower court, the rating could be recalculated and the continuous enrollment advantage disappears. That is not a small risk. It is the single largest regulatory overhang on the thesis.
Valuation is the other constraint. CLOV’s price-to-sales ratio is roughly around 0.9 to 1.0 based on recent market data. The stock is no longer cheap on a sales basis, which limits how much error the execution can absorb.
The valuation ceiling on CLOV also reflects a broader sector dynamic worth understanding. Managed care names have been dragging inside healthcare even as biotech and innovation stories attract fresh capital.
Bottom Line
Clover Health is not a turnaround in progress anymore. It is a company that has already turned, is generating cash, holds the top Medicare quality designation, and recruits members year-round while its largest competitors fight regulators in court. The appeal risk is genuine and deserves a position size that reflects it. But the underlying business is structurally stronger than the stock’s modest valuation suggests.