November 12, 2026
Bonus Content: SBLK Reports Nov. 18. The Dividend Math Is the Point.
The Shocking Truth about the AI Bubble
In just 48 hours, a tidal wave of bad news battered AI stocks:
- Chip giant Intel dropped 29%…
- Google had its worst day ever, losing $500 billion in value…
- And tech stocks plummeted by more than $1 trillion in one trading day…
That’s more than $153 billion vaporized each hour!
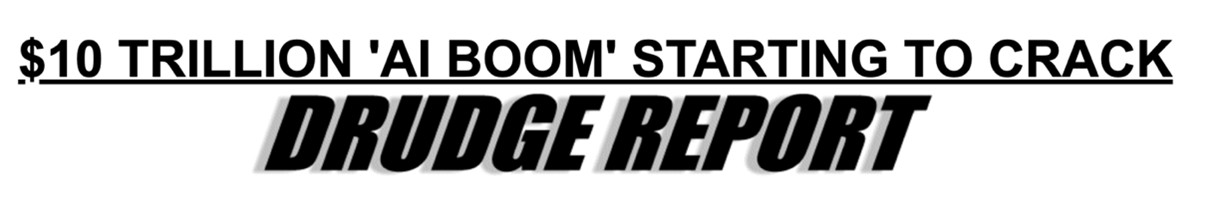
Top internet news site Drudge Report had this headline screaming at the top of the page…
“$10 trillion ‘AI Boom” starting to crack…”
So is the AI bubble finally bursting?
It sure as heck looks like it…
But here’s the shocking truth: it isn’t bursting for every stock.
On the same day Intel plunged 29%, the S&P 500 fell just 1.8%.
In other words, the stock market is splitting in two.
And the independent millionaire who recommended NVDA at $6 saw this coming.
He calls this stock market split the Great AI Shock.
On one side, the most hyped AI stocks could see a 77% meltdown…
On the other side, a little-known corner of AI that NVDA’s CEO calls a “once-in-a-generation opportunity” could produce triple digit gains over the coming months…
And the recent carnage is only the beginning – because the stock market split is just getting started…
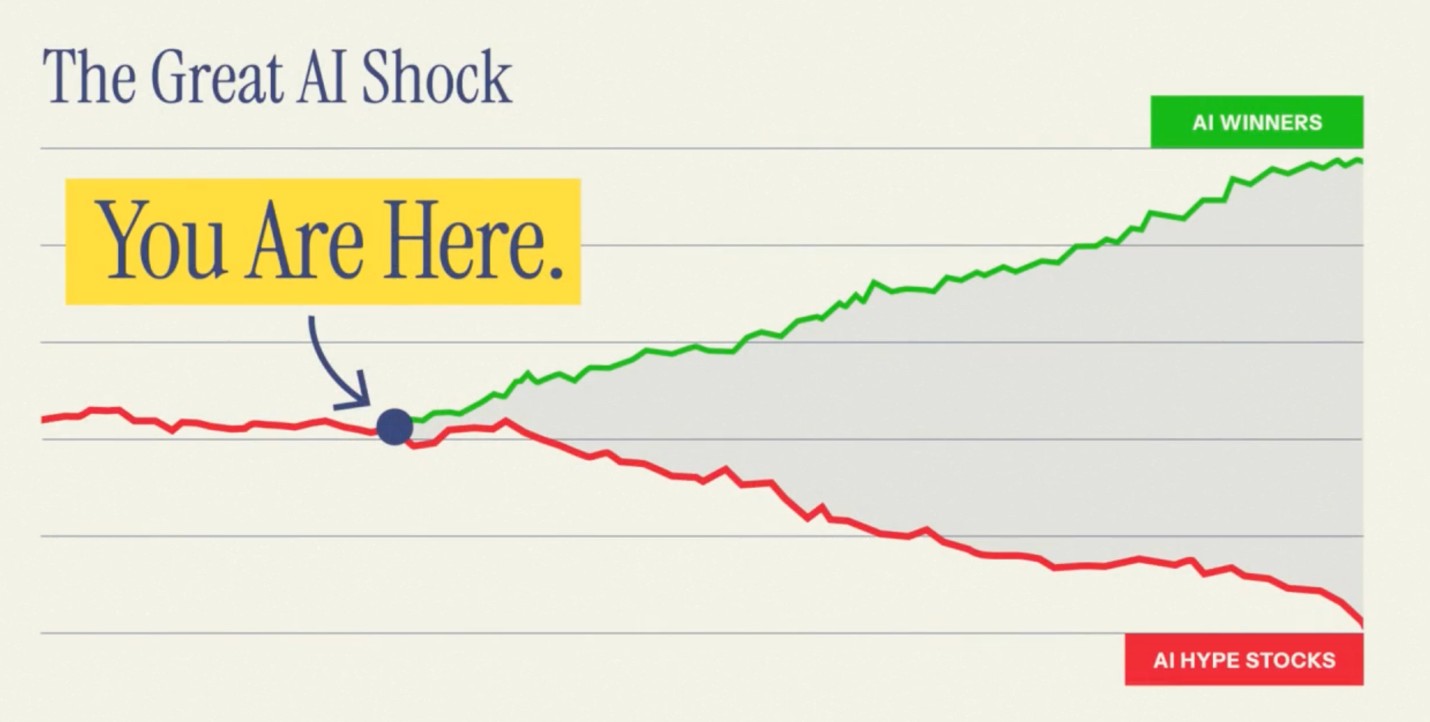
If you own any AI stocks, you need to decide which side of the split you’re on…
And you need to decide soon.
See the full story here, including details on the #1 stock on the right side of the split.
SBLK Reports Nov. 18. The Dividend Math Is the Point.
Star Bulk Carriers reports Q3 results on November 18, 2026. Six days. Analysts are split on the number, with consensus estimates clustering around $1.30 per share on revenue near $320 million. What matters more than whether SBLK lands a penny above or below those figures is what the number implies for the next dividend check.
That is the actual investment question here, and most coverage misses it.
Star Bulk operates a 100% cash flow distribution policy alongside a $100 million share repurchase authorization. That is not a marketing line. It means the quarterly dividend moves directly with earnings, up and down, quarter to quarter. For anyone sizing a position today, the payout is not a yield you model once and forget. It is a live read on the dry bulk market itself.
The two most recent quarters make the trajectory clear. Star Bulk posted net profit of $58.5 million in Q1 2026, declaring a $0.50 per share dividend, then followed with its strongest quarterly result since 2022, a $144.9 million net profit in Q2, and a $0.90 per share dividend. The underlying driver was a sharp jump in daily rates. The daily time charter equivalent rate hit $24,486 per vessel in Q2, up from $13,624 in the same period a year earlier.
The market entering Q3 looked supportive. Capesize spot earnings moved back above $30,000 per day in late October, with the Baltic Exchange reporting the BCI 182 5TC rising from $30,518 on October 19 to $34,380 by October 23. That October lift does not feed directly into September quarter averages, but it matters for how the market is framing the Q4 run-rate heading into the November 18 report.
The structural backdrop, however, carries a catch. Iron ore futures in Singapore traded below $90 a ton in October, touching about $89 intraday on multiple occasions. Sustained pressure there can trim export volumes from marginal producers and dull vessel utilization at the margin. An aging, capital-intensive fleet operating in a market where dry bulk growth projections already look muted is not a thesis-breaking risk, but it is a real one that rate strength alone cannot paper over forever.
Iron ore is not the only commodity where supply-side stress is complicating a bullish rate narrative. BHP’s copper production fell 19% year on year even as prices hit records, a reminder that mining output and commodity prices can diverge sharply.
The balance sheet provides meaningful cushion. As of June 30, 2026, Star Bulk reported roughly $565 million in cash and cash equivalents and about $1.04 billion of total borrowings. Since 2021, the company has returned about $13.49 per share in dividends, based on its own disclosures earlier this year. At Wednesday’s open of $27.36, that cumulative return relative to current price is a figure worth sitting with.
Analysts broadly carry a consensus moderate buy rating, with a widely quoted average price target of about $31.50 against a share price around $27 to $28. The gap between those two numbers is not wide enough to make SBLK a screaming value on price appreciation alone. The case rests on income: a fleet of 138 vessels, variable dividends tied to real commodity flows, and a Q3 report in six days that will either confirm or complicate the second-half outlook. Watch the dividend declaration, not just the EPS line.