October 18, 2026
Bonus Content: Newmont Reports Thursday. How Much Gold Profit Stays?
Dear Reader,
Former Wall Street Journal reporter Jeff Opdyke has spent decades tracking global wealth shifts.
And right now, he believes most people are looking in the wrong place when it comes to AI.
They think the opportunity is in AI stocks.
He strongly disagrees.
In fact, Jeff says the biggest retirement opportunity tied to AI may have nothing to do with tech stocks at all.
Instead, he believes it’s happening somewhere much less obvious…
In a part of the system that becomes more valuable the bigger AI gets.
That may sound surprising.
But it’s the same kind of thinking Jeff used years ago when he identified America’s natural gas boom long before it became obvious – including pointing readers toward Cheniere Energy when it was trading around $5 a share in 2011.
Today, it trades above $250.
Now he believes another major shift is forming.
And this time, he says everyday Americans may be able to position themselves starting with less than $150.
He calls it The Surprising AI Retirement Strategy.
You can see his full presentation here.
It’s one of the more interesting retirement ideas we’ve seen in a long time.
Sincerely,
Ben Murnane
Producer, The Surprising AI Retirement Strategy
Newmont Reports Thursday. How Much Gold Profit Stays?
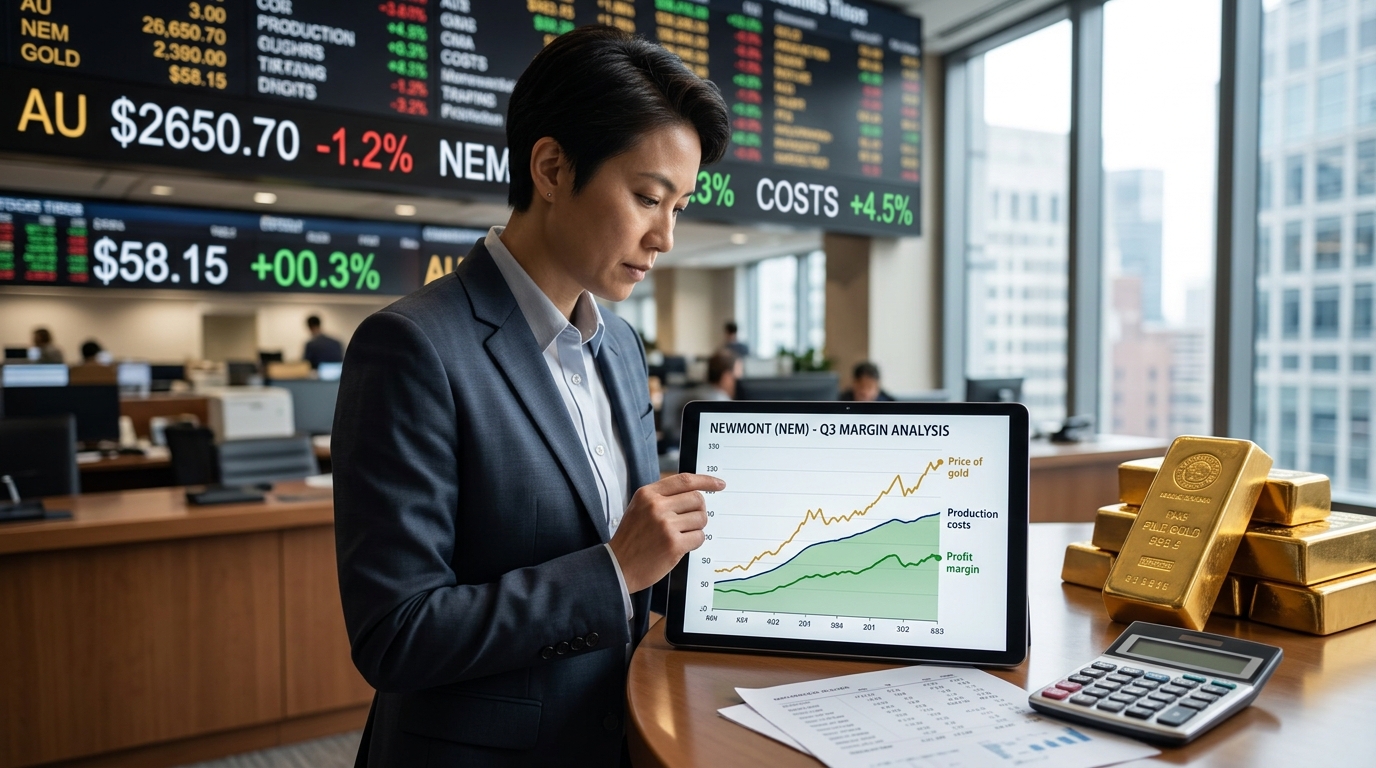
Gold settled at $4,164 an ounce on Friday, down roughly 4% from about $4,332 it traded one month ago and a long way from the January 2026 record highs. That softening arrives four days before Newmont reports third-quarter results after the close on October 22. The real question Thursday is not whether Newmont beats a number. It is how much margin per ounce the company actually keeps at today’s prices, and whether the $6 billion buyback authorized in April survives a spot price that keeps slipping.
What’s Driving the Market
Start with the math. Newmont’s full-year all-in sustaining cost guidance sits at $1,680 per ounce. At $4,164 gold, the theoretical per-ounce margin is approximately $2,484. In the second quarter, when Newmont realized $4,414 an ounce, that margin reached $2,734, about $250 wider than current spot implies for Q3.
Gold closed the third quarter near $4,150, and management had already signaled that sustaining capital would be weighted to the second half of the year, pushing unit costs higher than the $1,621 recorded in Q2. Fewer ounces at higher unit cost, on a softer realized price. That combination is the structural challenge Thursday’s report has to answer.
Production compounds the issue. Attributable output in Q2 was 1.3 million ounces, down from 1.4 million ounces in Q3 last year, partly reflecting the divestiture of non-core assets and lower grades across several mines. Management guided Q3 production broadly in line with Q2. That is not a recovery; it is another quarter at a lower run rate.
The Street consensus centers on approximately $1.96 per share on roughly $6 billion of revenue, representing around 15% earnings growth from the $1.71 and $5.52 billion Newmont reported in the same quarter last year. Whether Newmont hits that mark hinges on where realized prices and unit costs actually landed.
The Investment Opportunity
Newmont has beaten consensus estimates in seven of its last eight quarters. The board’s $6 billion share repurchase program, authorized in April after exhausting prior authorizations, absorbed $1.9 billion in Q2 alone through dividends and repurchases combined. At narrower margins, that pace slows. Buybacks funded by free cash flow depend on free cash flow; a softer realized price and higher sustaining costs squeeze both.
The most instructive number Thursday will be the Q3 AISC figure. If Newmont holds costs near $1,700, the margin at $4,150 gold remains defensible. If sustaining capital pushed costs materially higher, the production shortfall becomes harder to offset with price alone, and guidance for Q4 will carry disproportionate weight for GDX and the broader mining sector.
Risks to Monitor
A further decline in gold, driven by dollar strength or a shift in Federal Reserve rate expectations, would compress margins faster than Newmont can adjust spending. The roughly $550 million in Yanacocha water-treatment costs planned for 2026 also represent a cash drag regardless of spot gold. On the other side, timing effects or provisional-pricing impacts could put Q3 realized prices above $4,200, enough to drive a meaningful beat and support continued buyback activity.
Bottom Line
Newmont earns a per-ounce margin most producers can only envy even at current prices. The problem is that Q3 captured the downswing from this year’s highs, with production flat and costs rising. Whether the $6 billion buyback continues at full pace or pulls back is the real read on management’s confidence in where gold goes from here.