Market Snapshot
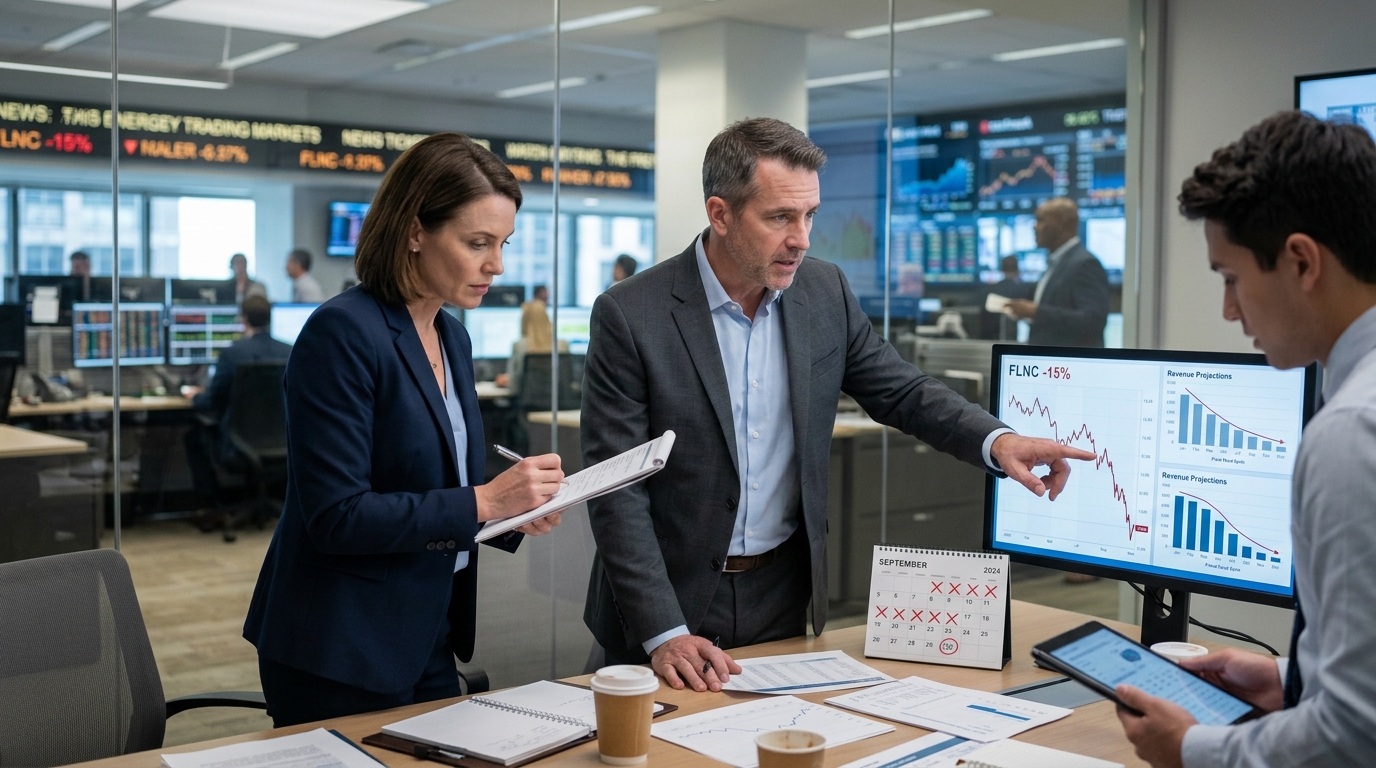
FLNC is the energy-storage name dominating trader screens this morning. On September 16, Fluence revised its fiscal year 2026 guidance, cutting expected revenue to about $2.4 billion from a prior midpoint of $3.0 billion and widening its projected adjusted EBITDA loss to roughly $200 million, largely due to persistent delays ramping its U.S. contract manufacturing in Houston. Guidance had already been revised downward last month when the company released Q3 fiscal 2026 results, from earlier guidance of $3.2 billion to $3.6 billion revenue to between $2.9 billion and $3.1 billion.
Two cuts in roughly five weeks, with twelve days left in the fiscal year.
Stocks in Focus: FLNC
The adjusted EBITDA loss guidance now stands at approximately $200 million, compared to a prior midpoint loss of approximately $10 million. That is not a rounding error. It means the company went from near-breakeven to deeply in the red, and did so twice, on the same problem: a Houston contract manufacturing ramp that has not delivered.
Fluence attributes the cuts mainly to continued delays ramping its Houston contract manufacturing facility, while noting strong demand and a functioning international supply chain. Management stressed that the order book is real. Supply chain constraints and delays ramping its Houston contract manufacturing facility are choking that backlog into slower, less profitable revenue. If you can’t ship on time and at decent margins, backlog is just a number on a slide deck.
On September 16, Fluence Energy closed at $9.05. The next day, after the guidance reset, the stock finished at $7.66, a steep two-day slide from $9.30 on September 15 and from above $11 just a few weeks earlier. Intraday swings were wide. Intraday action on September 17 shows FLNC opening near $7.23, flushing to about $7.01, and then bouncing toward the high $7s.
Sector Watch: Leadership Changes and Wall Street Reaction
Fluence Energy overhauled its leadership in mid-September 2026, appointing AES veteran Bernerd Da Santos as COO, installing AES CFO Stephen Coughlin on its board, and terminating Chief Product Officer Peter Williams to strengthen operational oversight and governance ties with key shareholder AES. The COO hire is pointed directly at Houston. Da Santos will oversee Fluence’s customer success, product, supply chain, manufacturing, and enterprise operations organizations.
Wall Street is not waiting for results. Barclays downgraded Fluence Energy to Underweight from Equal Weight and cut its price target to $10 from $16, pointing to the gap between the big backlog and weak near-term earnings visibility, along with higher capital needs and softening liquidity. Mizuho lowered its FLNC price target from $15 to $8 and reiterated Underperform. Piper Sandler kept an Underweight rating and cut its price target to $5 from $6, warning margins and adjusted EBITDA are likely to stay well below Street expectations through FY2027 and FY2028. Baird downgraded the stock to Underperform with a reduced price target of $3 amid ongoing production delays at its Houston plant.
Catalyst Calendar
Fluence’s FY2026 concludes September 30, 2026. Fluence plans to provide a detailed business plan and financial update for fiscal 2027 when it reports fiscal 2026 results. That full-year report and the 2027 outlook are the next hard catalysts, and the range of analyst targets, from $3 to $10, suggests no consensus on what those numbers will show.
Technical Radar
The daily chart shows a steady downtrend, lower highs from the mid-$11s in late August to just above $10 in early September, then a drip into the $9s as traders leaned cautious. Intraday, FLNC recently traded in a tight band around $7, with most five-minute candles stuck between about $6.90 and $7.20. That tells you the panic gap lower has already happened, and now short-term traders are battling it out in a narrow range.
Watch the $7 level. A hold there keeps a base intact. A break targets the Baird $3 scenario in the minds of the most bearish analysts.
The Cheat Sheet
- Top Market Theme: Execution failures in domestic manufacturing are punishing energy-storage stocks harder than demand weakness would.
- Stock to Watch: FLNC, with the fiscal year ending September 30 and a wide analyst target range from $3 to $10 signaling that this is unresolved.
- Sector to Watch: Grid-scale energy storage. AES remains a major Fluence shareholder and accounts for its investment under the equity method, so AES carries direct exposure to any further deterioration.
- Biggest Risk: Management targets neutral to positive operating cash flow in fiscal 2027 without relying on external capital, but if Houston does not ramp before then, that goal requires a second belief.
- One Thing to Remember: Demand is not the problem. The issue is converting a large backlog into shipped, billed revenue, and Fluence has missed that execution bar twice in five weeks with twelve days left on the clock.