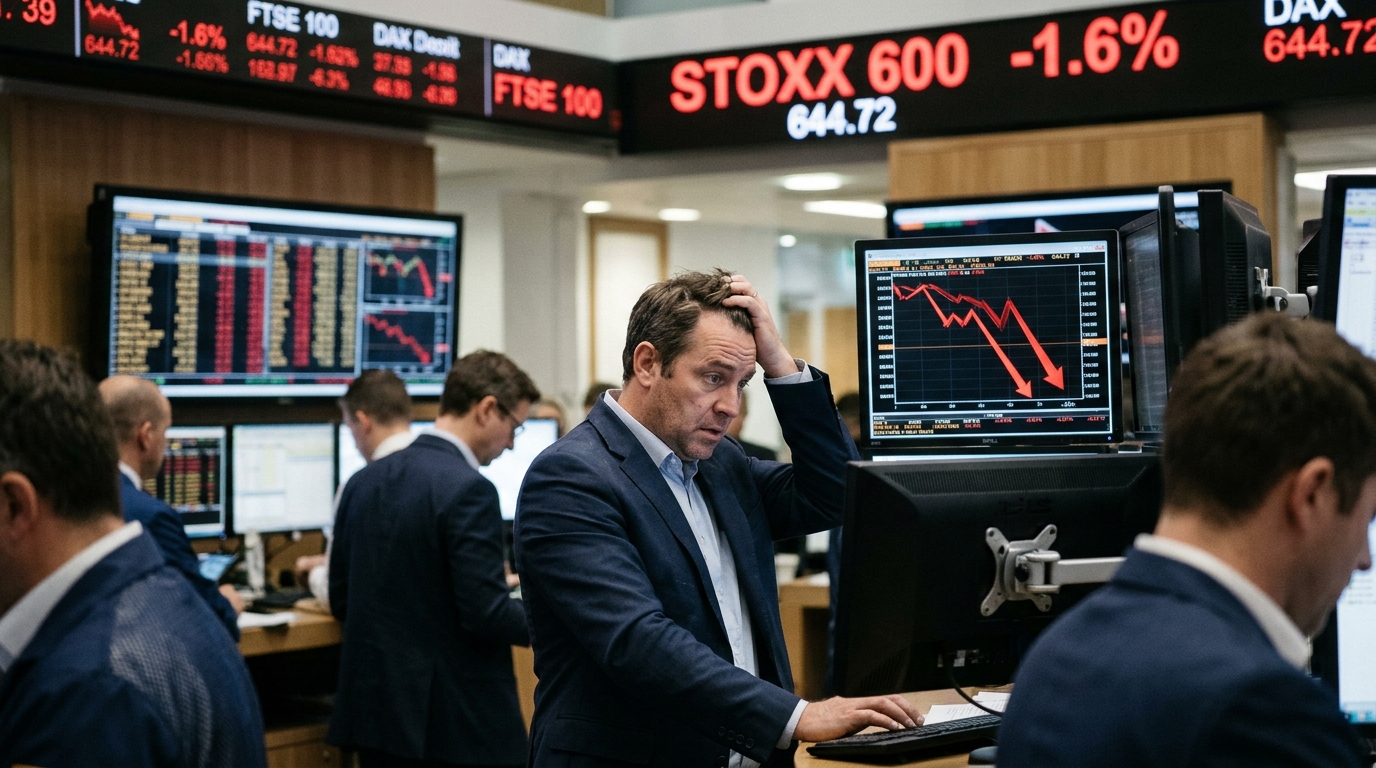
The diversification argument for European equities died quickly this week. For roughly two trading days after Democrats swept Congress in Tuesday’s midterms, the Stoxx 600 held its footing while Wall Street and Asia convulsed. By Friday morning in London, it was gone. The pan-European STOXX 600 dropped 1.6% to 644.72 points, with benchmarks in most major regional markets down more than 1% each. Friday’s losses wiped out the index’s gains for the week entirely, leaving it down about 0.2%.
Media, healthcare and retail led the broad-based declines, each falling over 2%. These are not AI-linked sectors. That is precisely the point. When a selloff crosses from semiconductors into retail and hospitals, the thesis that Europe was insulated because it had less AI exposure collapses. Fears that a Democrat-led Congress could seek curbs on AI data-centre spending added to concerns already building over weak returns, lofty valuations and debt-fuelled investment.
The chain of events that forced Friday’s reckoning started Thursday in America. The Nasdaq Composite declined 5.52% to close at 24,315.00, sliding into correction territory more than 10% below a record set last month, while the S&P 500 dropped 4.36% to end at 7,353.73. Nvidia lost 9.3% and AMD plunged 17.3% as investors reduced exposure to AI hardware. The Philadelphia Semiconductor Index fell sharply for the week and was on track for its worst weekly performance since early April 2025.
Asia had no floor to find. Japan’s Nikkei 225 fell further on Friday and was widely described as being in, or effectively at, bear-market territory, more than 20% below its June peak. The slide was led by chip-related stocks, including a plunge in Japanese chip-testing equipment maker Advantest. In Seoul, the damage was worse. South Korea’s Kospi plunged as much as 8.8%, triggering a trading halt and briefly falling below the closely watched 5,000 level. Samsung Electronics and SK Hynix each shed more than 9%. It was the 11th circuit breaker triggered this year on the Korean exchange.
The damage to chip-equipment and memory names across Asia reflects a broader pattern in semiconductor markets. TSMC’s experience shows how even record-breaking fundamentals can fail to protect a chipmaker when macro sentiment turns against the sector.
For precious metals investors, the European collapse matters beyond the equity losses it represents. Gold is trading near $4,050 this morning, pressured rather than supported by the turmoil. Spot gold slid on November 6 as stocks and bitcoin sank, a rare break from its safe-haven role that traders link to forced selling. The mechanism is straightforward: when margin calls arrive across equity portfolios of this scale, liquid assets get sold first, and gold is among the most liquid assets on earth. Margin calls after the AI-stock selloff forced some investors to sell liquid assets, and higher-for-longer rate expectations added pressure.
Gold’s correlation with equities is not reliably positive over time, but the two can move together during liquidity shocks. The metal has lost roughly a quarter of its value from its 2026 highs, after the United States and Israel began strikes against Iran on February 28, as spiking energy prices and expectations of tighter monetary policy have diminished the allure of the non-yielding metal. Analysts also note that central banks have been a consistent source of demand in recent years, though there is no fixed price level at which they reliably step up purchases. That dynamic, if it holds, may be the more important signal coming out of this week’s wreckage.
The honest read on diversification right now: there is none in the conventional sense. Every major equity market is correlated to the AI trade to some degree, because the AI trade had become a primary engine of global growth expectations. The selloff bled into wider equities, underscoring just how much the AI boom has been propping up overall economic growth. When that engine stalls on regulatory fears, the contagion is not limited to tech indices. It shows up in European media stocks, Korean chip foundries, and the gold futures curve simultaneously.
The question for precious metals investors is not whether gold will recover. It may, particularly if central bank demand stays firm and safe-haven flows return. The question is what kind of recovery: a quick technical bounce once forced selling clears, or a genuine return to safe-haven inflows once equity markets stabilize. The answer depends heavily on whether Congressional Democrats follow through with actual AI regulation or whether this week proves to be a fear-driven overshoot. Either way, the European hedge is off the table.