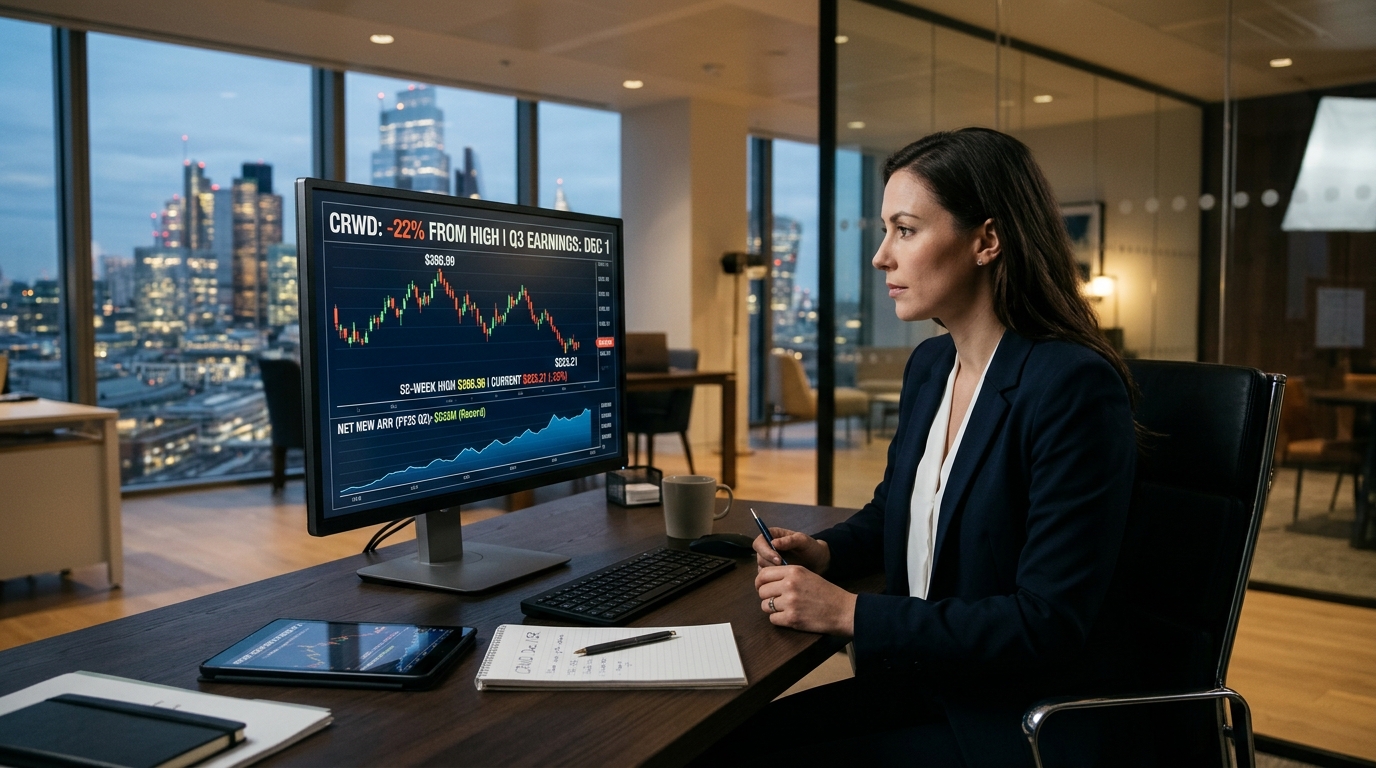
CrowdStrike’s stock hit $286.99 this year. It closed Monday at $223.21. That is about a 22% decline from its 52-week high, and it happened while the underlying business was accelerating. The gap between the stock and the fundamentals is what makes December 1 consequential, not just for CRWD holders but for anyone trying to understand what the market is currently willing to pay for elite cybersecurity growth.
The Business
CrowdStrike sells cloud-native endpoint security, identity protection, and threat intelligence through its Falcon platform. Its model is built on annual recurring revenue, which is why net new ARR is the single metric that determines whether the premium valuation is justified. Net new ARR hit a record $333 million last quarter, up 51% year over year, a meaningful acceleration over the 32% growth reported in the previous quarter.
Management raised its full-year net new ARR growth outlook to 34% at the midpoint, compared with its original 20% to 25% projection. CrowdStrike also moved its long-term target of reaching $10 billion in ARR forward by one year to fiscal 2030, compared with $5.84 billion recorded at the end of July 2026.
Why Wall Street Is Paying Attention
The pullback from the October high brought analysts out with raised targets rather than downgrades. On November 16, Cantor Fitzgerald raised its price target to $275, citing strong checks, ongoing momentum in platform consolidation, core endpoint detection acceleration, and continued success in security information and cloud products. Wells Fargo has a $300 target with a Buy rating, reiterated on November 16. TD Cowen is at $280, also Buy.
The threat environment is also doing CrowdStrike no harm. Reuters reported in October that CrowdStrike said a China-based actor likely used an AI agent to hack South Korean banks. AI-assisted attacks mean the security perimeter keeps expanding, which keeps the buyer’s urgency high.
For the December 1 quarter, company guidance implies revenue of $1.52 billion to $1.53 billion. For the full fiscal year ending January 31, 2027, company guidance implies revenue of $5.99 billion to $6.01 billion and non-GAAP EPS of $1.25 to $1.26.
What’s Driving the Opportunity
The stock is off its high because of two things: a broader tech selloff driven by rate anxiety, and CEO selling. CEO George Kurtz has sold shares under a Rule 10b5-1 trading plan. The stock’s valuation is also demanding, and management’s Q3 outlook implies net new ARR growth slowing from the prior quarter’s 51% pace. For a business compounding at this rate, any deceleration in that growth metric gets punished immediately.
The bull case rests on two things. First, platform consolidation: enterprises are replacing multiple point solutions with a single Falcon deployment, which is driving multi-product upsells and extending contract length. Second, AI security: the December 1 report will show whether AI-focused offerings and expansions add enough ARR to support the premium.
What Could Go Wrong
The valuation remains extreme by any traditional measure. At roughly $220 per share, CrowdStrike trades at about 40 times sales on recent revenue. The stock needs every quarter to confirm acceleration. One miss on net new ARR and the correction that began in October continues.
According to consensus estimates, normalized earnings per share are expected to increase from $0.93 in the year ended January 2026 to approximately $2.12 in the year ending January 2029. Even using that forward EPS, the stock would still trade at a very high multiple of three-year-out earnings. That is a lot of confidence to price in before a December earnings report where the CEO has already been selling shares.
The Bottom Line
CrowdStrike is one of the market’s most prominent AI-era cybersecurity franchises, and it is off its high with a record ARR quarter behind it and a December 1 report ahead. The 51% acceleration in net new ARR last quarter is exactly the kind of inflection that justifies the premium. What it does not justify is complacency about valuation. The entry point matters here more than it does in almost any other stock. Investors who want exposure should size accordingly and watch the ARR number on December 1 above everything else. That single figure will determine whether the pullback was opportunity or warning.