September 19, 2026
Three central banks moved in 48 hours. Wednesday’s surveys are the first look at what broke.
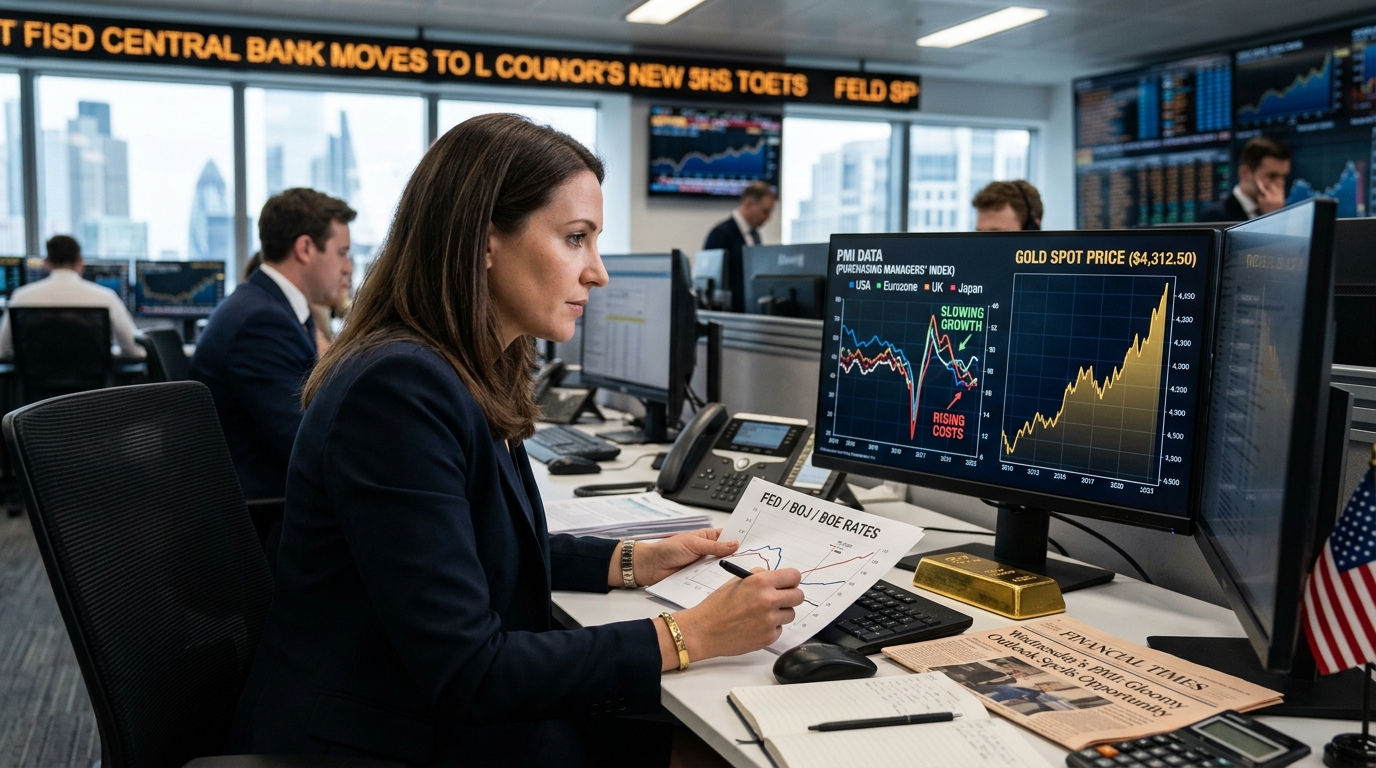
Gold settled near $4,300 on Thursday after a week that saw three major central banks move within 48 hours of each other. The Federal Reserve raised its benchmark rate by a quarter point to 3.75%–4.00% on September 16, signaling scope for further increases. The Bank of Japan raised its benchmark rate to 1.25% on September 18, the highest level since 1995. The Bank of England’s Monetary Policy Committee voted 6–3 to maintain Bank Rate at 3.75% in September. That is a lot of policy to absorb in one week. The September flash PMIs, arriving Wednesday at 9:45 a.m. ET, are the first surveys collected entirely after all three decisions cleared. They are also the first surveys collected after diesel set a record high.
He went 11-for-11 during the last Fed shock. Another one is about to hit.
In 2022, when the Federal Reserve made its most dramatic pivot in history and the S&P lost nearly 20%, Larry Benedict didn’t lose a single trade.
He knew where the money was going and positioned his readers to profit.
Trump is now installing his own Fed Chair, something Wall Street is already calling a generational shift.
Larry says his readers will be ready for it.
Click here to find out the one ticker he’s positioning in, completely free.
What’s Driving the Market
The average price of diesel hit $6.23 per gallon on September 14, the highest level on record, according to AAA. Since the war with Iran began in late February, the nationwide average diesel price has soared by about 60%. That matters enormously for PMI sub-indexes. Diesel is the fuel that moves freight, powers farm equipment at harvest, and sits embedded in the cost of nearly every manufactured good that gets shipped. Diesel feeds inflation directly through higher fuel costs, but more often the effect is indirect, through transportation and delivery costs that move through supply chains.
The August S&P Global US Manufacturing PMI already showed that pressure building. The flash reading eased to 53.2 in August from 53.9 previously, held back by higher fuel costs, reduced inventory building, and raw material shortages linked to supply delays. The services side was no cleaner: the ISM Services Prices Index registered above 70% for the fifth time in six months in August, and the 12-month average reached its highest since April 2023.
Wednesday’s flash PMI data covers the US, euro area, and UK simultaneously, with Japan’s print following Thursday. The surveys are collected mid-month, meaning the September figures will capture how businesses responded after the Fed hiked, after the BoJ reached 1.25%, and after diesel cleared $6 a gallon. Gold prices are expected to remain moderately volatile this week amid the release of preliminary September manufacturing and services PMI figures.
What 25 years on a Wall Street desk taught me about retirement income
I spent 25 years at Merrill Lynch and Vanguard watching the same play run, week after week, in every market condition imaginable. The money keeps coming in on every trade. Now that I’m on the outside, I’ve put together a free guide that breaks down exactly how this works, in plain English.
The Investment Opportunity
Here is the read that matters for precious metals investors: if Wednesday’s composite PMIs show headline activity softening while prices-paid sub-indexes stay elevated, that is textbook stagflationary data. Slowing growth plus sticky inflation is precisely the combination that strips central banks of their main tool. The Fed already hiked into a weakening manufacturing sector. The BoJ is at a 31-year high on rates while dealing with a yen that slid past 157 per dollar after the decision, despite the hike. Protracted Middle East conflict has contributed to further increases in crude and refined energy prices, and UK CPI inflation rose to 3.1% in August, likely to rise further.
Gold’s late-January record near $5,000 an ounce now sits well above current levels around $4,300. J.P. Morgan analysts expect gold to push toward $6,000 an ounce by year end. That call depends on a specific macro path: growth fading while inflation stays embedded. One strategist described it plainly: “You have a Fed Chair signaling higher for longer into a labor market that is visibly softening. That’s a stagflation setup, and gold tends to do well when the market starts questioning whether the Fed can hit both sides of its mandate.”
Japan’s figures deserve particular attention. Japan’s Manufacturing PMI stood at 54.5 in July, the seventh straight month of expansion, supported by the steepest rise in new orders in four-and-a-half years amid strong AI-related demand. A sharp reversal in the September flash print, especially combined with elevated input costs, would confirm that the BoJ hiked into a deteriorating industrial cycle. That scenario weakens the yen further, widens the US-Japan rate gap, and reinforces gold as the asset of last resort when all major central banks are effectively firefighting inflation rather than supporting growth.
5 Nasdaq Stocks Under $5 That Aren’t What You Think
Most stocks under $5 come with a reputation. These don’t.
Each company on this list is tied to major trends like AI, cybersecurity, and next-gen infrastructure.
They may not have the spotlight yet, but they are building real businesses in real markets. That combination is not always easy to find at this price level.
Risks to Monitor
The bear case is straightforward: if Wednesday’s PMIs surprise to the upside on activity while prices-paid readings ease even modestly, markets will interpret that as the soft landing holding together. Real yields could move higher on that data, and gold typically struggles when investors believe central banks can control inflation without breaking the economy. The new 2026 Fed dot points to one more hike, with the 2027 median signaling no further tightening, though eight participants still see rates rising to 4.25%–4.50%. A scenario in which growth holds and the Fed’s path becomes credible is the one that caps gold from recovering its January highs.
Protracted Middle East conflict driving energy costs higher remains the core variable no PMI survey can resolve. The BoE noted explicitly that the policy stance required to address that shock will depend on its scale and duration, both unknowns. Until those clarify, every PMI print sits in the same ambiguous territory: real economic activity softening, but the price signal too hot to ignore.
Bottom Line
Wednesday’s flash PMIs are not a growth report. Read them as a gold signal. A print that confirms slowing output alongside persistent cost pressures locks in the stagflationary case and justifies accumulating gold on any near-term weakness. The three central bank decisions this past week did not resolve the fundamental tension between tightening policy and rising energy-driven inflation. They merely reset the starting point. Wednesday tells us whether the real economy is absorbing that reset or breaking under it.