September 15, 2026
Bonus Content: Microsoft’s $678 Billion Backlog vs. a 5% Treasury
Dear Reader,
I’m writing to share our #1 stock to buy right now as the U.S. power grid cracks.
This company’s new tech is already live in remote fields in West Texas.
It can generate round-the-clock power without waiting years for the public grid to catch up.
This tech is now backed by Elon Musk.
And Meta, Microsoft, and Google are getting in too.
Satellite images have surfaced – that could soon show everyone what’s going on. So before the average person hears about this…
Click here to learn all about the #1 power grid stock to own right now.
Regards,
Joel Litman
Chief Investment Officer, Altimetry
Microsoft’s $678 Billion Backlog vs. a 5% Treasury
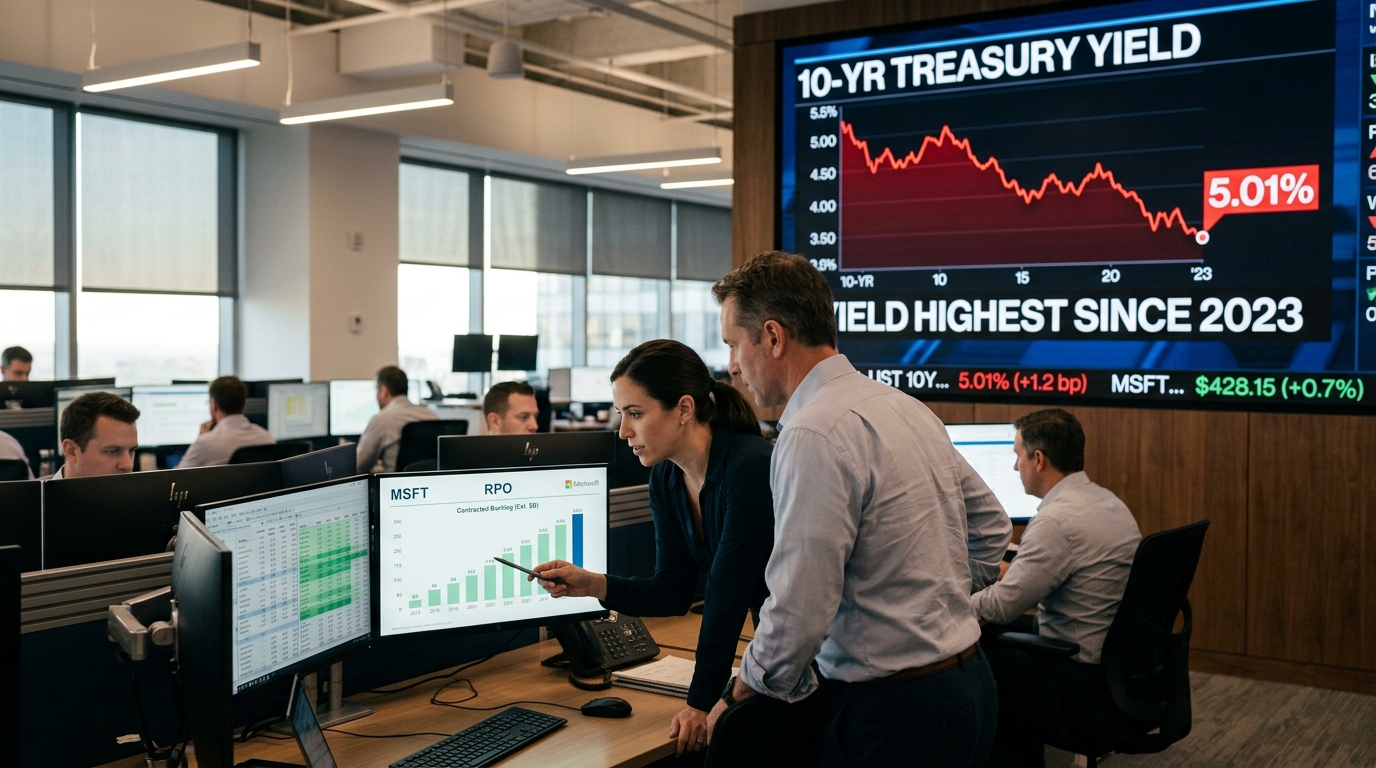
The 10-year Treasury yield briefly touched about 5.01% on Monday, a level it had not reached since 2023, as higher oil prices and renewed inflation worries kept pressure on bonds. Markets are pricing a high probability of a Federal Reserve rate hike on Wednesday. For most long-duration growth stocks, this is where the valuation math starts to break down. Microsoft is not most stocks.
Here is what the rate-sensitivity argument against MSFT typically ignores: the company does not need a favorable discount rate to justify its forward revenue. It has already collected the contracts.
A backlog that changes the math
Microsoft closed fiscal 2026 with a record $678 billion commercial remaining performance obligation, an 84% jump from the prior year. That figure, disclosed in the company’s fiscal 2026 results, represents enterprise revenue already under contract but not yet recognized. The backlog is now more than twice Microsoft’s $331.8 billion in fiscal 2026 revenue, and it reflects the value of contracts already signed but not yet recognized, including long-term Azure and Microsoft 365 commitments. When a DCF model applies a rising discount rate to speculative future cash flows, it destroys value. When those flows are already contractually committed, the damage is structurally smaller.
The operating numbers underneath that backlog are not soft either. Microsoft Cloud revenue was $54.5 billion in Q3 FY2026, up 29% year over year, with Azure growing 39% in constant currency. Operating income reached $38.4 billion, up 20%, and operating margin expanded to 46.3% from 45.7% a year earlier. Then in Q4, Azure accelerated further. Fiscal fourth-quarter revenue jumped 18% to $90 billion and Azure grew 43%.
The company’s AI business has reached a $37 billion annual revenue run rate, growing 123% year over year, confirming that AI workloads have moved from pilot deployments into sustained, billable cloud consumption. That is not a forecast. It is the company’s own reported run-rate metric.
The concentration risk hiding inside the headline
Investors should not take the backlog at face value. The $678 billion RPO jumped 84% from a year earlier, but CFO Amy Hood disclosed during the earnings call that the headline number includes a large contribution from OpenAI. Hood told analysts that commercial RPO “increased 25% when excluding OpenAI.” Strip out OpenAI and the organic enterprise pipeline still grew at a healthy clip, but the headline number overstates diversification.
Microsoft 365 Copilot surpassed 30 million paid seats, and together the backlog and Copilot adoption suggest enterprise AI demand is moving beyond experimentation into large-scale commercial deployments. That is the more durable revenue layer: recurring seat-based subscriptions that are far less sensitive to any single partner’s trajectory.
What this means for precious metals investors
The connection to gold is direct. The 10-year yield rose to about 5.01% on September 14, 2026, and a decision to leave rates unchanged on September 16, 2026 could put further upward pressure on Treasury yields if markets interpret such a move as undermining the Fed’s credibility in its fight against inflation. That same yield environment compresses the present value of long-duration assets across the board, which is why gold at current levels faces a genuine rival in risk-free government paper. Microsoft’s cloud backlog shows one way corporate cash flows can be structured to resist that pressure. The question for gold is whether central bank buying and inflation hedging provide equivalent insulation. Right now, the answer is contested.